Gooaye EP710 notes: he took his kid trick-or-treating in a costume two sizes up, and his watch logged the whole morning as high stress
Notes on the 31 October 2026 episode of Gooaye (EP710): Gooaye's host on chasing a bounce, sizing it too big, and only seeing his stress reading drop after he went home and cut it — plus the margin maintenance ratio at 130, four cloud vendors beating on demand while the stocks fell, Intel's substrate yields, and the quant-pod unwind trap. Educational notes only; no investment advice, no price targets, no stock picks. Figures are as spoken on the show and my reading may be wrong.
Contents
Some things are within our power, and some are not. Within our power are judgement, will, desire and aversion — in a word, whatever is our own doing. Not within our power are the body, property, reputation and office.
—— Epictetus, Enchiridion, ch. 1 (c. AD 125; my own translation)
In the 31 October 2026 episode of Gooaye (EP710), the host describes taking his son to a Halloween event at Taipei Children’s Amusement Park. His smartwatch marked him as being under high stress continuously from 8am to 12:30pm; at 12:30 he gave up, went home, trimmed his positions, and only then did the reading fall. The reason, he says, is that he chased the previous week’s bounce, bought too much, cut it again on Thursday and Friday, and ate a loss he never needed to carry. In the same episode he put Taiwan’s margin maintenance ratio at 130 with margin calls likely the following week, and noted that none of the four big cloud vendors flagged slowing demand — and the stocks fell anyway. Every figure below is as he spoke it; check the filings yourself before using any of them.
The L-size didn’t fit
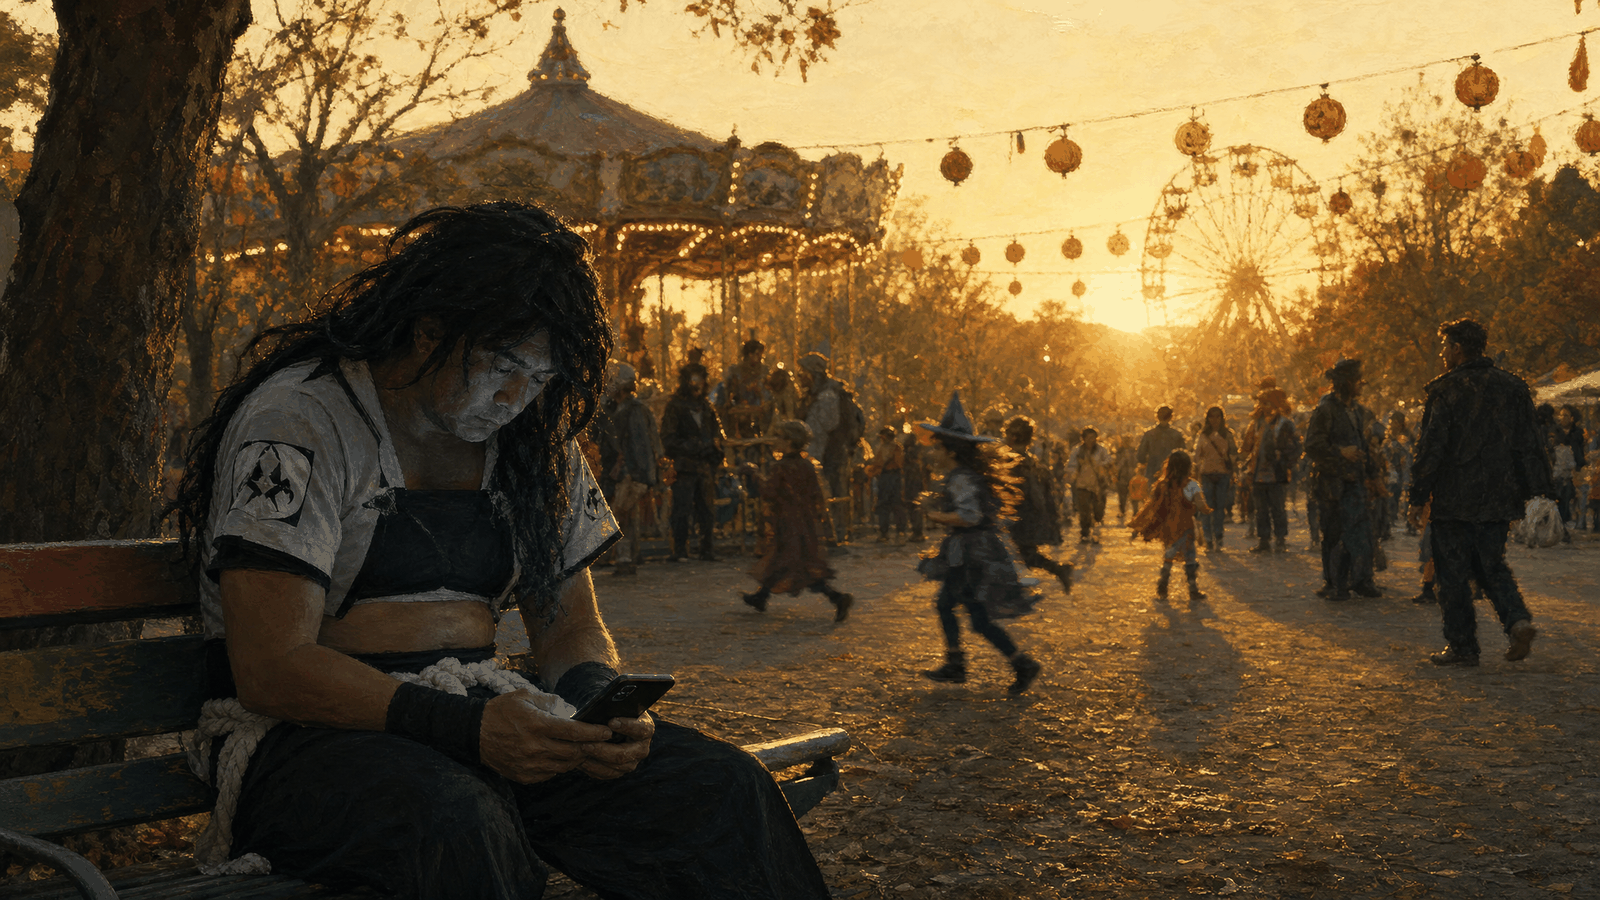
Start with the part that has nothing to do with stocks. He says his family used to put no effort into his son’s school Halloween event, until they noticed a classmate’s parents going all in every year — the Joker one year, Michael Jackson or Bruno Mars another — and decided they were slacking. His wife ordered a Sasuke outfit online: a crop top that bares the midriff over a black vest. The label said L and it would not go on. A 2XL did, barely, plus a wig.
The night before, everyone was happy. The problem was the date: 31 October. Taiwan’s market had already broken down that Friday, fell further over the weekend, and Monday was still coming. So he put on a wig that scratched his neck and a 2XL top he had squeezed into, and went to his son’s school event.
The watch started recording at 8am
Taipei was hot that day — the typhoon had passed and the sun came out hard. He says he spent the whole morning “performing”: playing with his kid, taking photos, posing with listeners who recognised him, thinking about something else the entire time and wanting the wig off.
Later he looked at the watch log and found the morning written down: from 8am to 12:30pm, flagged as high stress the whole way. The 12:30 turn had nothing to do with the market, which had not steadied; he simply couldn’t take it and said he was going home. He trimmed his positions, and the stress index dropped immediately. He adds that he has no idea how the watch detects it.

The same day he ran into another trading parent from the neighbourhood who never once took his phone out. Watching him, the host wondered what exactly he himself was doing there. That neighbour later joked that if they’re going to keep attending these events, they should size their books down for a few days either side — because the last Halloween also ended badly.
He went back and did the arithmetic
This is the part of the episode I keep coming back to, because he counts the cost honestly.
He held through the earlier bounces without chasing. The picture in his head, he says, is one of those Mel Gibson battle scenes where someone yells “Hold!” — don’t launch too early, wait for the moment, then charge. Through those bounces he watched other people chase in and get sold into the close, and admits it felt good, because he wasn’t the one being fooled.
Then a bounce arrived that he judged to be the real thing, off a level he thought looked clean, and in he went — and this time he was the one fooled. The position wasn’t huge, but he accepts that he bought too much, that it broke his rhythm, and that Thursday and Friday he had to cut what he’d chased. Two details make the bill worse: at those prices the stuff had already become relatively cheap, so there was no rush to sell; and the reason he sold was that he’d exceeded his own size limit and had to come back down. He frames the loss as a penalty he had to accept.
He also refuses the god’s-eye view — if that bounce had run, he’d have been taking the credit. So he argues it in probabilities instead: back in that moment, the rational version is to scale in slowly rather than push a lot at once.
Then he turns to leverage. His book used to run hot; now it barely uses any, so even sitting through another 2008 he survives — losing his shirt, but never margin-called into debt. He credits older friends and mentors for this: once you’ve managed to build a base, the thing you fear most is going back to being poor, or taking a risk you never had to take. Broke and starting out, you shrug and bet the lot. Now blowing up is off the table.
”Every print was good and the stocks still fell — I don’t get it”
He is not the only one stuck on this. He read through that week’s cloud numbers: Azure up 48% and accelerating, Google Cloud by his count above 100%, AWS around 40%, Meta’s advertising around 30%. Not one of them flagged slowing demand; all of them said demand exceeds supply. Then the stocks blew up.

If you have to pick a reason, he says, look at the cash-flow line. Microsoft’s quarterly free cash flow was positive, somewhere above US$18bn, and the stock held. Meta’s quarterly free cash flow turned negative; Amazon’s trailing twelve months is negative too. Put that next to the recent trouble at several Neo Clouds — the newer outfits that rent GPU capacity — and the market’s story may be rotating: from “spend whatever you like on AI and we’ll reward you, and punish you for not spending” towards checking whether the balance sheet holds up.
He points at the irony. At the start of the year, who would have guessed the two strongest names today would be Apple and Microsoft? For the past year Apple’s narrative was that it had been left behind by AI and was wasting the resources it had, while Microsoft got written off as an old ox pulling a cart. The two least-loved megacaps have the best price action. He notes he was not heavily positioned in either and did not call it.

Google is the stranger case. Run his thought experiment: suppose six months ago someone handed you the inside line that Google was about to ship a model that would beat the market’s write-off of it. Wouldn’t that feel like seeing the lottery numbers early — buy more now, because the market will re-rate it on the news? The model landed at the top, and the stock fell more than ten per cent.
His definition of a treacherous tape is a good one. If I call AI growth for the quarter, it shrinks, and the stock craters, that’s on me — my analysis was poor and the punishment is deserved. It gets treacherous when the analysis and the judgement are both right and the market hands you nothing back. Bad news that won’t fall means a rally is coming; good news that won’t rally means a drop — and you start trying to front-run everyone else’s front-running.
Once a tape gets there, he says, his move is back to fundamentals, back to Investing 101: stop imagining narrative and re-rating, buy the next few years of cash flow, find whoever’s business is good and sit on it. He immediately names the condition under which that fails — sitting in value names is no guarantee of winning; sometimes the high-multiple names get killed first, flush out all the margin, and then keep ripping, and your whole framework stops matching the tape, which is agony. So his choice is to take an already conservative book and make it more conservative, and rest when he can’t read it.
Intel is the same lesson in another form. On the call after the close on 29 October, he says, the company described datacentre growth as its strongest in fifteen years, with demand ahead of supply and plenty of customers wanting to build AI. That matched his own guess. The stock got punished anyway, and the headlines went to the weak PC client business squeezed by memory prices — something everyone already knew and he has covered many times. He also points at where Intel is genuinely stuck: Intel 3, the process behind Granite Rapids, is being expanded in Ireland while Oregon isn’t in production until the second half of 2027; and EMIB advanced substrates are short, with substrate yields under 50%. None of that used to hurt a stock, because supply shortfalls solved are just money. Now it goes on the charge sheet.

He puts 2022 alongside it. In late 2021 the fashionable claim was that whoever held more inventory would see more orders, because once the long-lead parts arrived they could finally ship. Then rates rose, war broke out, demand jammed, and all that inventory became inventory to work off — a painful year. Today, he says, AI supply-chain valuations already trade on something like thirty times three years out, which means you cannot miss a single print. On the industry side, the scenario he thinks is easiest to see is Neo Cloud funding breaking, half-finished builds and ordered equipment coming back onto the market — not enough in volume to matter, but plenty to hit sentiment, with consolidation behind it.
”The tape is awful, so why are some names still going up?”
This is the part of the episode I most wanted to write down.
He says some non-AI semiconductor names have been trading well lately, that friends of his noticed too, and then lays out the trap: it isn’t necessarily rotation. Multi-manager quant funds run many pods, each with a manager and strict long-short constraints. When volatility rises, the top takes capital back, or a pod’s performance slips and it gets cut down, they have to unwind — every dollar of longs sold comes with shorts bought back. And the semis with little AI exposure are exactly what had been shorted.
So you see something odd: one day there’s heavy buying from a foreign broker or some mysterious desk, and the price goes nowhere. That’s short covering, a hedge being closed, with no view on the fundamentals attached. Filter that layer out, he suggests, and you can finally see what is genuinely strong.
The use for a reader is direct. When the tape is bad, the instinct is to avoid catching falling names and buy whatever still looks strong — and this says strength has two possible sources, one where fundamentals carry it and one where someone is closing a book. Telling them apart means looking at who is buying and whether they’ll keep buying: covering is a one-off, and when it’s done it’s done.

He adds the Taiwan-specific wrinkle: US money rotating into software has plenty to buy, while Taiwan has almost no software to rotate into, and the smaller themes left over can’t hold up market-wide sentiment. So his shop is starting to shift back to its old trade early, looking for what’s worth watching outside AI — for a few years, he says, buying AI was the whole answer, consumer and auto bets got beaten like dogs, and he worries the easy years spoiled him.
As for the post-selloff ritual of hunting for the prophet who called it: his read is that Michael Burry keeps his following because of that one call, and the money from that one call doesn’t cover what you give up missing an entire bull run. He says they still don’t like being short and would rather look for the long side — while doing the teardown work either way.
Worth a look
- Gooaye EP710, 31 October 2026 — the source for these notes
- Intel’s Q3 2026 results and the 29 October call, to check the datacentre growth claim, the Intel 3 ramp timing and substrate yields
- The cash-flow statements in Microsoft’s, Alphabet’s, Amazon’s and Meta’s latest filings — pull the free cash flow line yourself and compare
- TWSE and TPEx margin balance and maintenance-ratio data, to see whether the margin sits in single stocks or in leveraged ETFs
- Data from the 2022 inventory correction, as a reference for how “more inventory means more orders” broke down
The one thing to take with you
Your position size decides whether you can still be a normal person away from the screen.
That watch of his is an honest instrument. What it measures isn’t how many points the index dropped — it’s how much he was carrying that he shouldn’t have been. Which is why the reading fell the moment he trimmed, and not when the market steadied. Through the earlier bounces he held, and this year he could laugh in photos with listeners and enjoy how ridiculous everyone looked. The days he’d chased in too big, the watch started logging at 8am.
That shape is everywhere outside investing. The favours you agreed to, the money you lent, the things on next week’s calendar, the projects running at once — all positions. Someone carrying up to their limit has to cut something the moment anything unexpected lands, and what gets cut in a hurry is usually the cheapest thing at that moment and the one you regret later — which is exactly how he came to sell a position he never needed to sell.

One thing I’ve tried: pick something already on next week’s calendar that you’d rather not be distracted during — your kid’s event, dinner with family, a friend’s wedding. Then today, write one line: which thing, if I don’t deal with it first, will have me checking my phone all day. Once it’s written, close it out before that day arrives; and if you can’t close it, shrink it down to a size you can carry and take that instead.
This article is an educational discussion of investment method. It is not advice to buy or sell any individual security, offers no target prices, and does not analyze any current holding. Investing carries risk; make your own decisions or consult a qualified professional.
Comments
Loading comments…