He Stopped at Kilometre Seven — Notes on Gooaye EP707
Notes on Gooaye EP707 (21 October 2026): a run cut short by the sun, a market where great earnings move nothing, the clean-room bottleneck behind substrate shortages, and how to recount your position after buying near the top. Educational, not investment advice.
Contents
A prickly head, sprung up among deep weeds, now rises slowly past the tangled scrub. Men of the age don’t know the cloud-climbing tree — they call it tall only once it tops the clouds.
—— Du Xunhe, “The Small Pine” (Tang, c. 9th century; my own translation)
In Gooaye EP707, released on 21 October 2026, host Hsieh Meng-kung told two stories that look unrelated. He stopped a riverside run at just past seven kilometres with his watch reading around 170 beats per minute, while the marathon veteran beside him sat at 120. In the same week he watched a company beat street expectations, heard Elon Musk say on the call that compute rents were still climbing and that payback could reach six months next year — and then saw the stock gain less than ten percent pre-market. His read: the fundamentals are fine, the price action is the odd part. So he trimmed and rotated rather than turning bearish. That reasoning holds only if you accept that fundamentals and prices run on different clocks, and that you need cash on hand to buy the next leg.
Kilometre seven, and he stopped
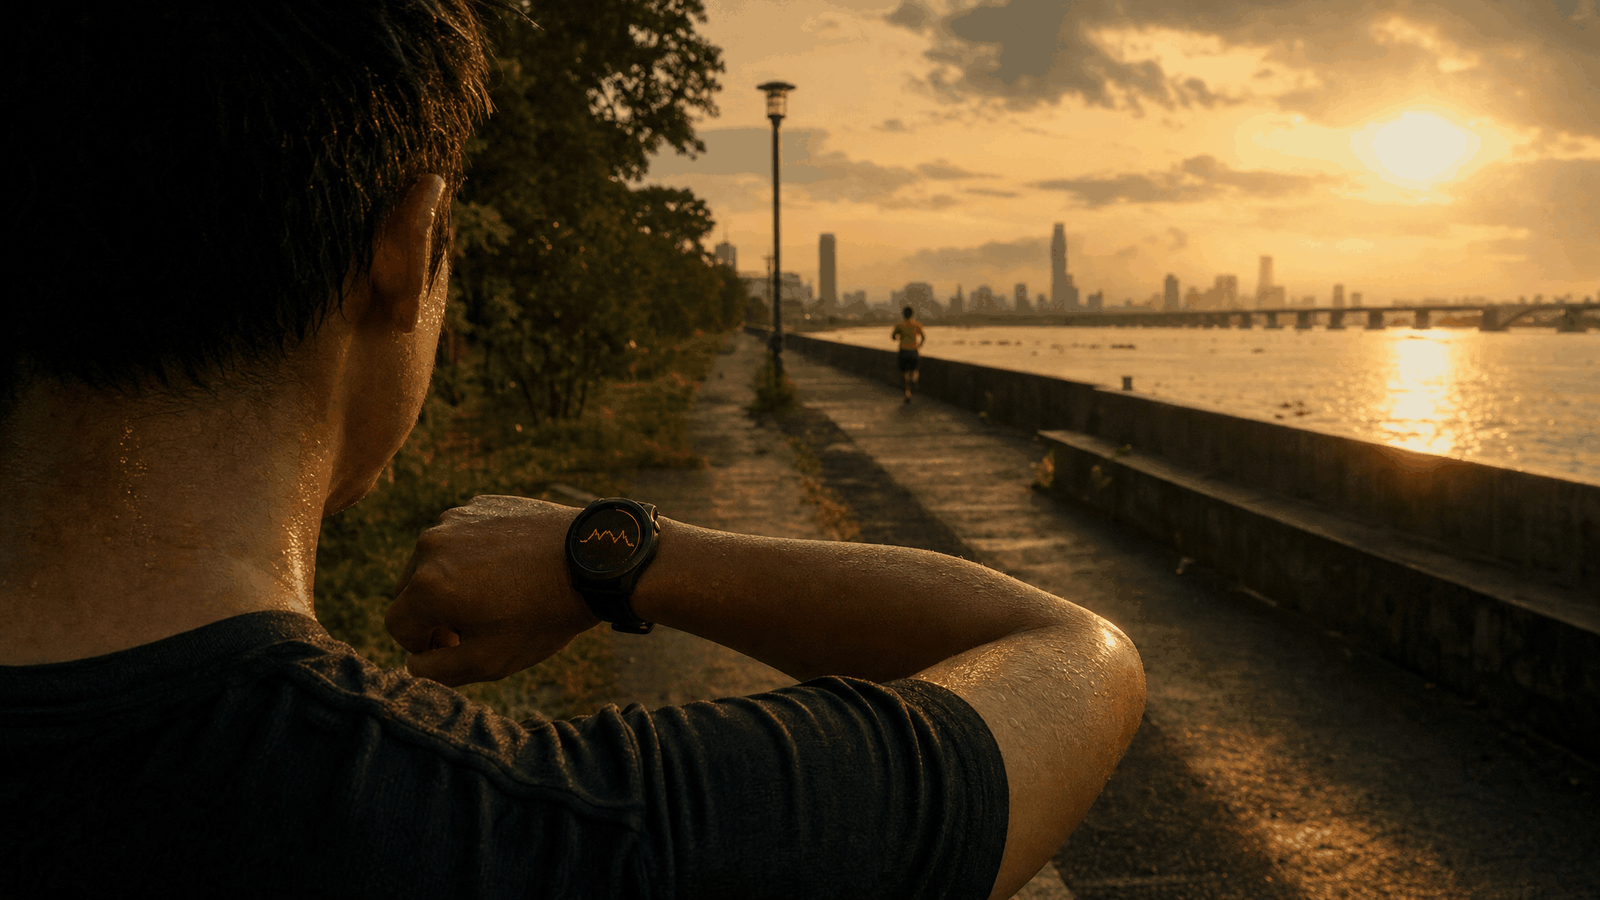
It was the hot spell before a typhoon, with the clouds swept away and no shade at all. He was training with friends along the riverside park, and by just past seven kilometres his head was swimming. The next two or three kilometres had no cover whatsoever, so he told his friend he was done.
He listed what went wrong: a black running shirt that soaked up heat, no cap. The reason those details matter is that you cannot reason your way to them. You have to reach kilometre seven before you learn that what you were missing was a hat.
The number on the watch
The second part is the one that stayed with me. He said he hadn’t felt tired, yet his heart rate made no sense. Same route, same pace: the experienced runner next to him at 120, him at 170. He suspects medication pushes his rate up by ten to twenty percent, and he admits his aerobic base isn’t there yet — he finished the distance by grinding through it.

His body said “fine.” The instrument said “not fine.” He sided with the instrument and changed his training. Most of us do this in the opposite order with money: we wait until the account looks ugly, then go hunting for a story that justifies how we felt.
Out of that came a habit worth stealing. He treats a goal as a checkpoint along a route rather than a finish line — ten kilometres now, twenty-one later, with a test at each marker. He compared it to school exams: he hated them as a kid, and now that nobody sets them for him, setting his own has become interesting. He runs the same loop at work, reviewing performance every quarter so corrections happen mid-route instead of in December.
That week, a very good set of numbers
On the morning of the recording, Musk’s company reported revenue, connectivity and superintelligence growth all above expectations. He said the satellite internet figure startled him — he hadn’t expected that user base to deliver at this point in the cycle.
What caught his attention on the call was contract duration. The market had been waiting for the company to lock in long-term compute agreements; Musk said they want short ones, because compute prices keep climbing, revenue per watt keeps rising, and payback could hit six months next year.
There’s a supply-chain rule of thumb buried here that he’s repeated for years: once vendors start signing long contracts and locking prices, that cycle is often near its peak. The logic is that the side which had been raising prices relentlessly now wants a fixed number, which means it has smelled something and wants a hedge. Insisting on short contracts points the other way.

He fenced off the six-month figure carefully. That number belongs to an operator whose execution outruns the field — when a data centre build stalled on turbine fan lead times, they simply manufactured the part themselves. Others, he said, are hearing 14 to 20 months.
But the tape ignored it
Great numbers, under ten percent pre-market. He said it felt off.
The same oddity is sharper in Taiwan. He sent friends to the circuit board and substrate trade show, and they came back describing a sector in celebration — shortages reaching into equipment and high-end upstream materials. Several of those stocks were making new lows.
His explanation, which he labelled as a guess: too many Taiwanese companies have good fundamentals right now. Below fifty percent revenue growth, he joked, you shouldn’t even speak up. Everyone is good, capital is finite, money clusters in a few groups, and the rest wait their turn. He described a cluster with two cheap names and two expensive ones. Theory says buy the cheap ones; his muscle memory said buy the expensive one, because its chart looked better and expensive things tend to get more expensive. His friend’s reply: you’re not wrong, we’ve tested this many times.

He left the question open rather than wrapping it up. Maybe the market hasn’t noticed yet. Maybe that earlier modest rally already priced everything in.
The bottleneck is the clean room
So when does the substrate shortage clear? Taking the chain apart, the first blockage sits in construction, not tooling. On ASML’s call, part of the shortfall was attributed to customers’ clean rooms not being ready. No clean room, no equipment install; no install, no capacity; no capacity, no relief.
The other route is yield. The show cited market chatter of roughly 50–60 percent on some substrate products and 20–30 percent on a packaging variant, with his own contacts arguing the real figures run lower — if yields were genuinely at 50–60, volume production would already be happening. Fixing yield means either working engineers into the ground or building double the capacity to make the volume anyway. He apologised to the engineers in his audience, then said that grinding really is one of the methods.
The twist: he checked the clean-room names, and they don’t move either. Every link in the chain is a verified bottleneck, and every share price does its own thing.

When you own something good that won’t move
This is where listeners get stuck. You did the work, the fundamentals check out, you understand the shortage — and it drops anyway. Were you wrong?
Three layers hold up here. First, separate “the company is good” from “the stock will rise.” His old image: the price is the dog, the fundamentals are the owner. The dog runs ahead and falls behind, but it doesn’t get lost. Prices overshoot and undershoot; divergence over months is normal. He offered a filter for toxic commentary too — anyone praising fundamentals on green days and trashing them on red days is worth closing the tab on.

Second, rewrite “will it rise” as “when does money rotate here.” Between two names you like equally, the one whose numbers land sooner usually goes first. That’s why so few people abandon momentum: where the money sits tells you more about the next quarter than the quality of the business does.
Third, accept the part you can’t explain. He has no answer for the substrate group’s price action, so instead of manufacturing a reason, he adjusts size — trimming what’s stuck, rotating into what’s working, keeping cash. He stressed this has nothing to do with his fundamental view; his position in the market is large enough that he needs cash available to add.
If you bought near the top
Another listener wrote in, accused of refusing to cut a loser, convinced it will come back if he just holds.
Instead of a verdict, he split the behaviour in two. One version is driven by sunk cost — holding because selling makes the loss real. The other is simply conviction plus bad timing: the year you started looking at stocks was the year prices were where they were, and those were the companies available.
Then the warning: cutting is not automatically the rational choice. He’s watched plenty of people stop out and then chase back in higher, losing twice. The three honest options are averaging down, freezing the position and waiting without adding, or cutting with a plan to re-enter. What matters is knowing which one you’re doing, and whether your grip on the business justifies holding.

Someone else asked about four consecutive limit-downs with no exit. He said four would have him wanting out too. If you entered on chart signals and don’t know the company, averaging down into limit-downs is catching a knife. If you’ve studied the roadmap and judge this to be panic or index drag, adding becomes defensible. His sharpest point: there are traders who crack limit-down boards open to trade the bounce, and their cost basis was set that day — nothing like a large position stranded at the top. What they can do isn’t what you can do.
Sources worth checking
- Gooaye EP707, released 21 October 2026 — everything recounted here comes from that episode
- Quarterly results and analyst call from Musk’s company, reported 21 October 2026
- ASML’s Q3 2026 call, including remarks on customer clean-room readiness
- TPCA Show, Taipei Nangang, October 2026
帶得走的一件事
Feeling fine is not being fine. You need a gauge that won’t make excuses for you.
He didn’t feel tired, and his heart rate was 170. Those Taiwanese companies posted beautiful numbers, and their shares broke to new lows. Same structure both times: the subjective reading and the objective one can sit far apart, and most of us only check the instrument after something breaks.
Here’s something I’ve tried that has nothing to do with investing. Pick one thing you’d describe as “fine” — sleep, weight, monthly cash flow, how long since you called a particular friend — and find a number for it that your feelings can’t argue with. Write it down. Measure again on the same date next month. No target, no habit change, just let the number exist. Three months later you’ll know whether that “fine” was a fact or a line you’d been feeding yourself.
This article is an educational discussion of investment method. It is not advice to buy or sell any individual security, offers no target prices, and does not analyze any current holding. Investing carries risk; make your own decisions or consult a qualified professional.
Comments
Loading comments…