One Strikeout at the Tokyo Dome, and the Fake Skill a Batting Cage Builds
Notes on Gooaye EP700 (2026-09-26): Meng-Kung Hsieh played his second real baseball game at the Tokyo Dome — one hit, one strikeout — and used it to talk about the false confidence of simulated trading, the trust barrier facing Meta's new pocket device, and why momentum traders are currently grinding each other down. Educational personal notes, no investment advice.
Contents
Virtue withers without an adversary.
— Seneca, On Providence (c. AD 64, my own translation)
In the 26 September 2026 episode of the Taiwanese podcast Gooaye (EP700), host Meng-Kung Hsieh describes playing the second real baseball game of his life at the Tokyo Dome: one hit, one strikeout. Back at the hotel his wife told him the hit was a scrappy one — the ball dropped early through a gap and he only reached first because he runs fast. He connects this to simulated trading: in a batting cage nine out of ten pitches are strikes, the bad ones are obviously bad, and the machine’s delivery is displayed on a screen, so anyone can learn to crush every ball. In the same episode he reviews the keychain-sized device Meta showed at Meta Connect 2026, noting that its predecessors (a $699 AI pin, a $199 handheld, a $99 pendant) are mostly dead, that he personally would buy this one, and that the thing blocking it is trust — in the survey he cites, roughly a third of Americans would hand their passwords to Google, versus 8% for Meta. These are his personal readings; a different product cycle or a different market regime would not support the same conclusions.
He rented the Tokyo Dome, then struck out
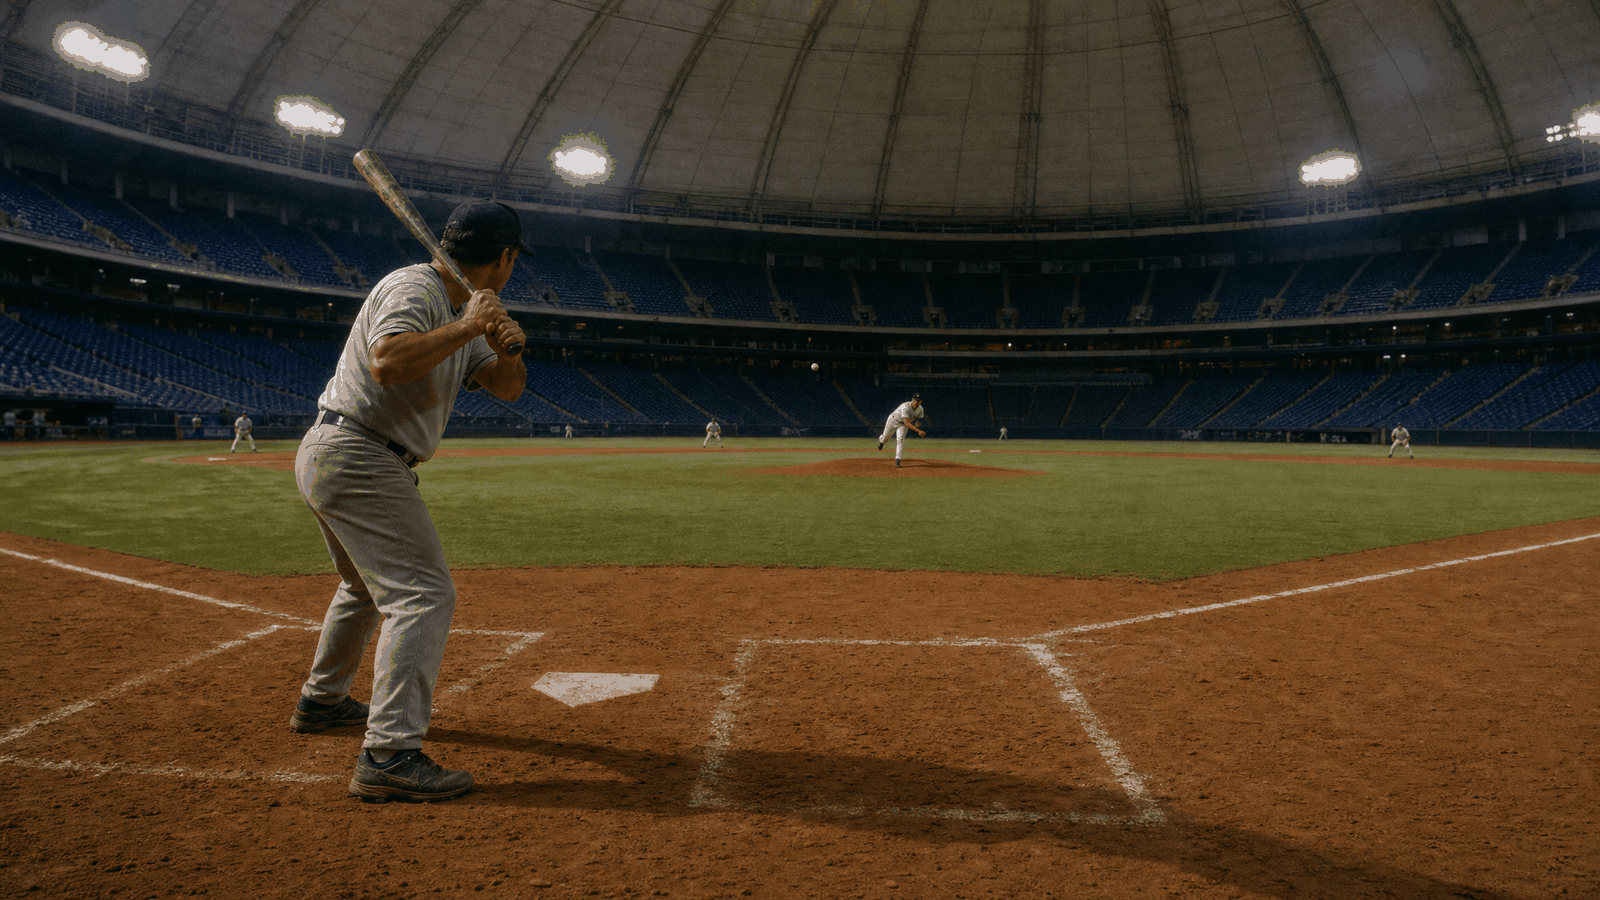
The episode opens on Mid-Autumn Festival. He flew to Japan with his elder son, because there was a game. His team had rented the Tokyo Dome — he says he had no idea you could rent it. What surprised him more was that the venue still staffed it like a real event: ticket checks and bag checks at the gate, a home plate umpire inside, Japanese staff keeping score.
They played a loose round first, letting everyone take three swings, then moved to the real game. He got a hit and logged it as an achievement. In a later at-bat he struck out, and his mood collapsed. The loop in his head was: I’ve trained at the batting cage for months, how did I strike out? He notices the reaction is odd — flying to the Tokyo Dome to play with friends is a joyful thing on its own, and one strikeout painted over all of it.
There’s a small detail I liked. Before the trip he considered bringing his own bat, the one whose colour and pattern he had picked out carefully. He left it home, and says that was lucky: showing up with the coolest bat in the building and getting struck out would have been worse. He files himself under gear guy — equipment first, technique later.
His wife said the hit was scrappy
He reported the box score to his wife, leading with the strikeout. She misread it as hitting the ball out and congratulated him. He clarified, then added that at least she’d seen the hit. She said the hit was scrappy — the ball landed early, squeezed between fielders, and his legs did the rest. Then she asked the real question: why can’t you launch it here the way you do at the batting cage?
His answer is the part of the episode that stuck with me: that’s the gap between the real thing and the simulation. In the cage nine of ten pitches are strikes, the bad ones are unmissable, the delivery is on the screen, and a few hundred repetitions hand you the pattern. A real pitcher doesn’t follow your pattern, and the pressure scatters your mechanics. He goes straight to trading: everyone discovers they’re a genius in a paper account, because the questions are fixed and no real money is bleeding.
I paused there. I get the same illusion running backtests — nudge the parameters and the equity curve becomes beautiful enough to make you want to size up. But a backtest has no slippage panic, no checking your phone at 3am, no colleague asking after three red days whether you didn’t say you had a system. His strikeout, translated into my world, is the first day I run a system with real money.
He adds a less romantic note: the functional training, the prep for a four-kilometre run — none of it done properly, a bit of this and a bit of that. And yet it helped. His sprint to first base held up. Practice doesn’t vanish; it shows up somewhere you weren’t aiming.
He turned around and his son was gone
Two of the other fathers brought sons, college-aged by the look of them, and the rapport startled him. The father leaves a mess on base, the son comes in and strikes the batter out; the father films the son’s at-bat, the son cheers and films the father’s, and they tap each other on the way past.
In his own frame of reference, kids stop wanting anything to do with their dad around high school. These men showed him a different outcome: never harsh, letting the kid grow into a shape he likes, staying beside him. Raise one that way and he’ll still take the field with you.
He was thinking I want moments like that with my son when he turned around and his son was gone. A message to his wife came back: we’re at the Pokémon café, your son got bored and left. The boy is five, and he says he won’t push him to match those older kids now. But he set it as a career goal: that at fifteen or seventeen his son won’t be embarrassed by him, and will be glad to enter something together — any sport, dodgeball included.
This is the same problem as the batting cage, seen from the other side. Baseball has a cage. Raising a kid has none — no machine feeding fixed pitches, no screen telling you what’s coming. You only get to do it live, and a bad inning doesn’t reset.
”Am I the one the big money is hunting?”
Later listener mail arrives, and the letters rhyme. One writer died with everyone else in July, then entered a stretch of not knowing how to trade: bought one name and it got raided the next day, bought another and it froze, cut a loss and watched it rip the following session. He can’t take it out on his family so he bottles it, and asks what options exist besides buying charcoal under the pretext of a barbecue.
The thought underneath is probably: is someone targeting my account? I’ve had that thought too, usually after the third stop-out.
The reply has two layers. Technically, the writer is trading momentum — chasing strength — yet one of his holdings had already rolled over, so the entry logic wasn’t consistent. The harder layer: the number of people calling this market difficult is enormous, including the traders he rates as elite, who are also switching to swing-style handling. So who is actually selling into whom? Each other. The chaser sees a weak open, knifes out, sometimes doesn’t even wait for the session — a 6% gap down at the open, everyone hammering the exit, everyone cursing whichever idiot is dumping, and the idiot is the same crowd.
He offers a contrast. One momentum trader he knows sees a higher share of next-day gap-ups and holds, and the reason he gives is that he treats a position the way he treats a date: even one night in, he’ll take you for hotpot on Civic Boulevard afterwards and leave everything tidy. Most people run positions as one cut in, one cut out.
One level up, he cites the upstream researcher Jeff: this is what Taiwan’s market normally looks like, and those wild momentum years were the last five. Those five years happen to cover half his trading career, so the fast tape he knows best is the exception. That line is worth keeping on its own — which sample trained your instincts, how long was it, how many regimes did it contain? A March-to-May stretch where boarding the train paid every time writes chase into muscle memory, and in a different regime that memory becomes a liability.
His own adjustment: same names, but buy the red days green — change the entry rather than the watchlist. To be clear, that’s his method, not an instruction to anyone. What I take is the order of operations: admit the regime changed, change how you enter, and only then question your stock picking.
Should you jump on the keychain now
On to hardware. His favourite thing from Meta’s event is the keychain-sized device: no price, no spec sheet, no pre-order, one line of official copy and an email signup box, with the specs dug out by supply-chain watchers. It looks like the toy pets we carried as kids, it holds Meta’s AI assistant, the avatar is swappable, and it talks to you whenever. One look and he knows he’ll buy it.
The reasoning around it is what I’d steal. He lines up the predecessors: the $699 AI pin with a $24 monthly subscription, whose assets HP bought before the service was switched off; the $199 handheld that was loud in 2024 and got written off as an app forced into a shell; the $99 pendant, discontinued after Meta acquired it. Their shared ambition was routing around the phone, and the phone is a brutal opponent — it’s the tablet from Zelda now, recording, shooting, tracking money, gaming, doing the work that used to need a PC. Displacing a device people depend on that heavily is a low-probability project. So he discounts the chain of reasoning that runs glasses become the next phone, therefore component demand explodes into the hundreds of millions of units: that whole chain stands on one assumption.
Why does he give this one a chance? Because Meta is already the incumbent. The startups were trying to route around giants; Meta doesn’t need to. People still use Facebook and Instagram, so moving its own users over puts it ahead of the field before the race starts.
What holds it back is the other thread in the episode: trust. In the survey he cites, roughly a third would give Google their passwords — lower than he expected — and 8% would give Meta theirs. He half agrees with the public, and his reason is behavioural: the scam ads flooding the platform repeat the same template for months when a filter would stop them, and the filter never arrives. Meanwhile the device only becomes useful once you connect Walmart, Best Buy, GAP, Sephora, PayPal and authorise the accounts — handing shopping and payment rights to a company you trust at 8%.
If your question is whether to adopt new tech now, my takeaway is to separate the two roles. As a user he’s happy to be the sucker: he knows talking an AI through a hotel booking is slower than clicking it himself in two minutes, and he wants the reps early anyway. As an investor the question moves one step earlier — who is this thing’s opponent, and what is actually blocking it? For this device the blocker isn’t component supply, it’s whether anyone hands over their accounts. Trust has no shipment schedule to track. You watch behaviour instead: the day those scam ads finally get filtered.
The one thing to take away
One idea: fluency earned inside a patterned environment impersonates ability. The cage throws nine strikes in ten and shows you the delivery, so your swing looks great. The backtest asks fixed questions, so your curve looks great. March to May paid everyone who boarded, so you feel like a chaser. All of that fluency is real — it’s fluency at that environment’s regularities, not at the thing itself. What matters is knowing which one you’re holding.
Here’s something I’ve tried that works today: take one thing you consider yourself fluent at, find a version of it that refuses to follow your habits, and do it once. The dish you cook in your own kitchen — cook it in someone else’s, with their pans. The explanation you give colleagues — give it to someone with no background, and watch which sentence loses their eyes. Don’t pick the thing you want to prove you’re good at; pick the thing you think needs no thought. That’s where the pattern hides deepest. Whatever falls apart is the pitch the cage never threw you.
This article is an educational discussion of investment method. It is not advice to buy or sell any individual security, offers no target prices, and does not analyze any current holding. Investing carries risk; make your own decisions or consult a qualified professional.