Code Words, Scapegoats, and a Choppy Tape — Notes on Gooaye EP698
From an indie booth at Tokyo Game Show to the AMD price-hike story and the CCL downgrade panic, plus an index at highs while everyone turns bearish. Listener notes on reading a bear case that only covers half the chain. Educational, not investment advice.
Contents
There was a kingdom on the left horn of a snail, called Chu; and a kingdom on the right horn, called Man. They warred over territory, and the corpses numbered tens of thousands. —— Zhuangzi, “Ze Yang” (Warring States period, translation mine)
In the second half of Gooaye EP698 (19 September 2026), the host turns to the supply chain and the tape. On the AMD price-hike headline, he says the component that moved most this round is memory, and TSMC was the last name on the headline. Against the CCL downgrade story, he notes that chip-to-chip links, PCIe Gen6 and CXL still run at rates that 10 to 25G material won’t carry, and he reads most of the downgrades as temporary. Traders turn bearish with the index near highs because individual names have lost continuity, so anyone watching daily sees their equity curve fall.
What this episode covers
Gooaye EP698 (2026-09-19) opens with a business trip to Tokyo Game Show and then turns to the supply chain: the AMD price-hike headline, the CCL downgrade panic that knocked the tape down intraday, and the observation I kept thinking about afterward — the index sitting near highs while online sentiment flipped bearish.
I was doing something else while listening and had to stop and rewind one section. It was the part where he explains why his own posts are written so that almost nobody can read them.
Key points
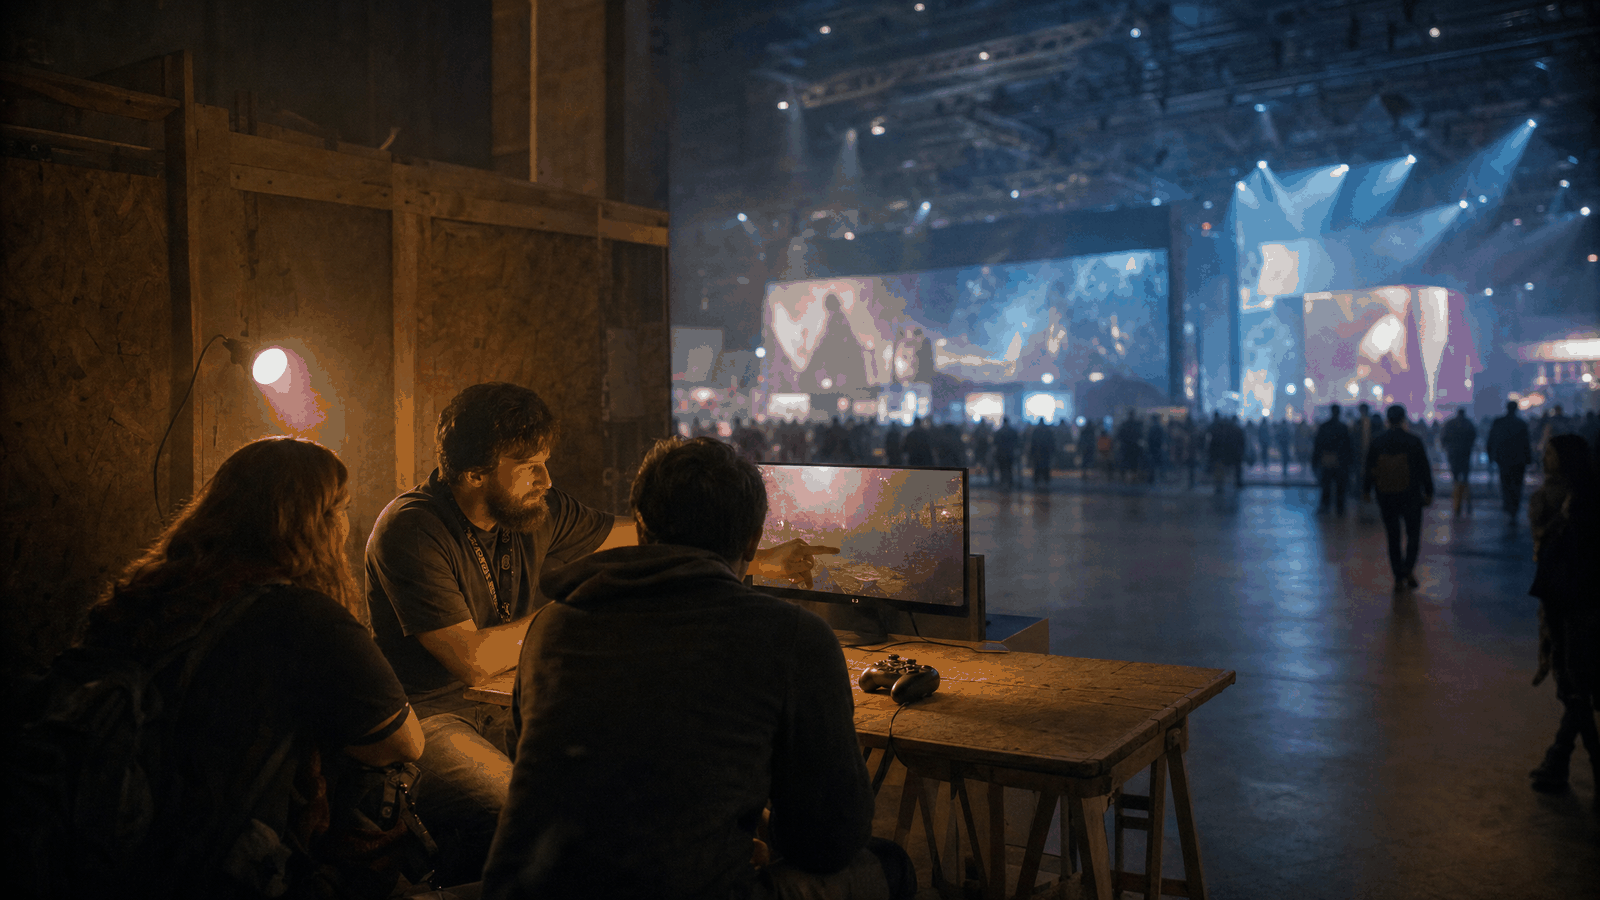
Big booths versus small ones. He noticed that the elaborate booths — booth models out front, five staff in matching uniforms handing out flyers — usually had the less interesting games. The booths where three guys crowded around a single screen and the founder did the explaining himself tended to have the better product. He was careful to say it was an observation, not a dig. What makes it useful: marketing budget and product quality are two separate lines, and when you can only see one of them, it quietly becomes your proxy for the other.
Cold outreach with a stack of business cards. He’s known enough in Taiwan that deals come to him. In Tokyo he had no such advantage, so he handed out cards knowing most would lead nowhere, smiling through it — something he says runs against his instinct to go home and talk to no one. A person with distribution, placed in a setting without it, finds out how many steps he normally skips.
His posts are code words, not articles. A listener pointed out that the show is plain-spoken while the posts read like stream of consciousness. He agreed and explained why: the show already spends all his effort on structure, so the posts became a signal — he only cares whether the people who recognize the keywords come back to trade information with him. His example was the phrase “CCL downgrade.” Inside the circle those three words unpack into a forum post, a specific day’s selloff, the pile-on that followed, the rebuttals from sell-side analysts. Outside it, they unpack into nothing. He wants the first group’s replies, and the cost is that the second group is locked out.
TSMC was the last name on the headline, not the main driver. He says a careful version of that AMD post would define who raised prices, on whom, by how much, and on which product line. He skipped all of it and opened with “MSRP isn’t a useful reference.” The reasoning: a graphics card’s bill of materials includes memory, passives, the board, the socket — all moving — while the suggested retail price lags. NVIDIA sells the GPU and memory as a bundle to board partners, so the increase surfaces in what those partners quote downstream, which is why consumers see prices climb with no official announcement. The component that moved most this round, he says, is memory.
Downgrades are emergency measures in an emergency. Fewer HBM stack layers, PCB material stepping back to M4, power supplies not rushing to 800V — he groups these together. Every link in the chain is constrained, so everyone is hunting for substitutes. He reads most of these as temporary, because as compute speeds rise, materials follow. His rebuttal to “high-speed signals convert to optical right beside the die, so the motherboard only carries low-speed control signals”: chip-to-chip links, PCIe Gen6, CXL storage all still run at high rates, and material rated for 10 to 25G won’t carry them. The argument covers one link and stops. He also flagged his own bias — older now, holding longer, disinclined to sell a leg and buy it back.
The index is near highs and everyone turned bearish. Turning bearish in July made sense, he says, because things were visibly breaking down. Turning bearish at highs is stranger, and the reason is that individual names have lost continuity: a breakout today, a break below tomorrow, a marginal new low, then a push higher. Zoom out to a month and the lows are rising. Watch it daily and your equity curve falls. He heard of a momentum trader already below his July lows — chasing strength each day, dumping when it failed to gap up, repeating until the money was gone. He quoted the host of Statementdog saying that over a longer history, this choppy tape is the normal one.
The market inflates a number and then deflates it. GB200 rack estimates went from 30,000 to 50,000 to 70,000, then came the cuts and the delays and the walk back to 54,000, 40,000. Dig into it, he says, and the original figure was 20,000. What fell was the expectation the market added itself.
Going deeper
”Bad news just dropped — should I get out?”
This is the one that traps me. A line appears mid-session saying some spec no longer needs upgrading, the related names collapse, you hold one of them, and you have ten minutes to decide.
The episode offers a check you can run on the spot: draw the chain the claim describes and find where it stops. The CCL argument covers optical conversion beside the die, and that part holds. It stops before the other high-speed traffic still crossing the board — processor to processor, expansion interfaces, storage interconnect. When a claim covers one link and concludes that an entire material layer is obsolete, there’s a gap in it. A gap doesn’t make the conclusion wrong. It makes it unproven.
Run the same check on the TSMC headline. Foundry raised 10%, therefore AMD raises prices — but a card’s cost structure has several buckets, and the one that moved hardest this round was memory. Once the attribution gets swapped, your follow-up work drifts with it: you go watch foundry pricing when the thing to watch is memory contract prices.
Three questions I ask now: how many links are in this chain, how far did the claim get, and what’s the current state of the links it skipped. If I can’t answer all three, I’m reacting to a headline.
”The index is at highs, so why is my account shrinking?”
This one hurts more, because it isn’t a wrong call. It’s a slow grind.
The mechanism he describes is familiar: buy the breakout, no follow-through the next day, stop out, rotate, buy the next breakout. Each individual trade follows the rules. Summed up, it’s a chain of small losses. The index climbs while your curve falls, and eventually you conclude the tape is unworkable and turn bearish — a conclusion grown from your equity curve, unrelated to where the index is.
Two separable things live in here. One is whether your holding period matches the tape’s current rhythm; breakout-chasing works in a trending tape and gets shaken out in a choppy one. The other is leverage. He mentions traders who intended to hold long, sized up, and got flushed anyway. Position size quietly rewrites your holding period: you think you’re swing trading for six months, while your actual tolerance lasts three days.
The line about choppy tapes being the historical norm is useful for resetting the baseline. Treat the last two years as normal and today looks like an aberration to wait out. Treat this as normal and the thing that needs changing is the method.
”Why can’t I understand what some people are saying?”
This part connects least to markets and interested me most.
He writes posts as signals to draw out people who already know, so they’ll trade information back. The same text carries enormous content for his target reader and reads as noise to everyone else. The trap: when we can’t follow a passage, we file it under “badly written” or “showing off.” There’s a third option — the passage wasn’t addressed to us.
You can tell which by the response the writer wants. Wanting comprehension, they define terms and give context. Wanting a reply from insiders, they drop keywords bare, because defining them drives the insiders away. Most short social posts belong to the second kind, and reading them by the first kind’s standard produces the impression that nobody explains anything.
It changed one habit of mine: when I hit a keyword I don’t know, I stop guessing at the writer’s intent and go research the underlying event instead. Once the event is clear, the code decodes itself.
Where to look next
- Gooaye EP698 (2026-09-19), available on major podcast platforms
- TSMC earnings call transcripts and investor presentations, on the company’s investor relations site
- Memory spot and contract pricing: TrendForce and DRAMeXchange public pages
- PCIe 6.0 and CXL specifications, at PCI-SIG and the CXL Consortium (for per-interface signal rates)
- Statementdog’s podcast, for the discussion of long-horizon market normalcy
One thing to take with you
A statement that makes you want to act right now has usually covered one segment of a longer chain. That segment may be entirely correct, and your decision still depends on the state of the segments it skipped.
Here’s something I’ve tried that works outside markets too. Pick something you were recently talked into — a job change, a purchase, a judgment about a person. Write the sentence that convinced you, word for word. Underneath it, write “three things this sentence doesn’t mention.” Fill all three and you know enough to decide. Come up short and it’s worth pausing to go find the rest. I used this last month on an impulse to replace a machine and got to item two before realizing everything I knew about it came from a single review.
This article is an educational discussion of investment method. It is not advice to buy or sell any individual security, offers no target prices, and does not analyze any current holding. Investing carries risk; make your own decisions or consult a qualified professional.