90% Equals Zero: How a Near-Bankrupt Japanese Parts Maker Reached a 20% Operating Margin on Punctuality Alone
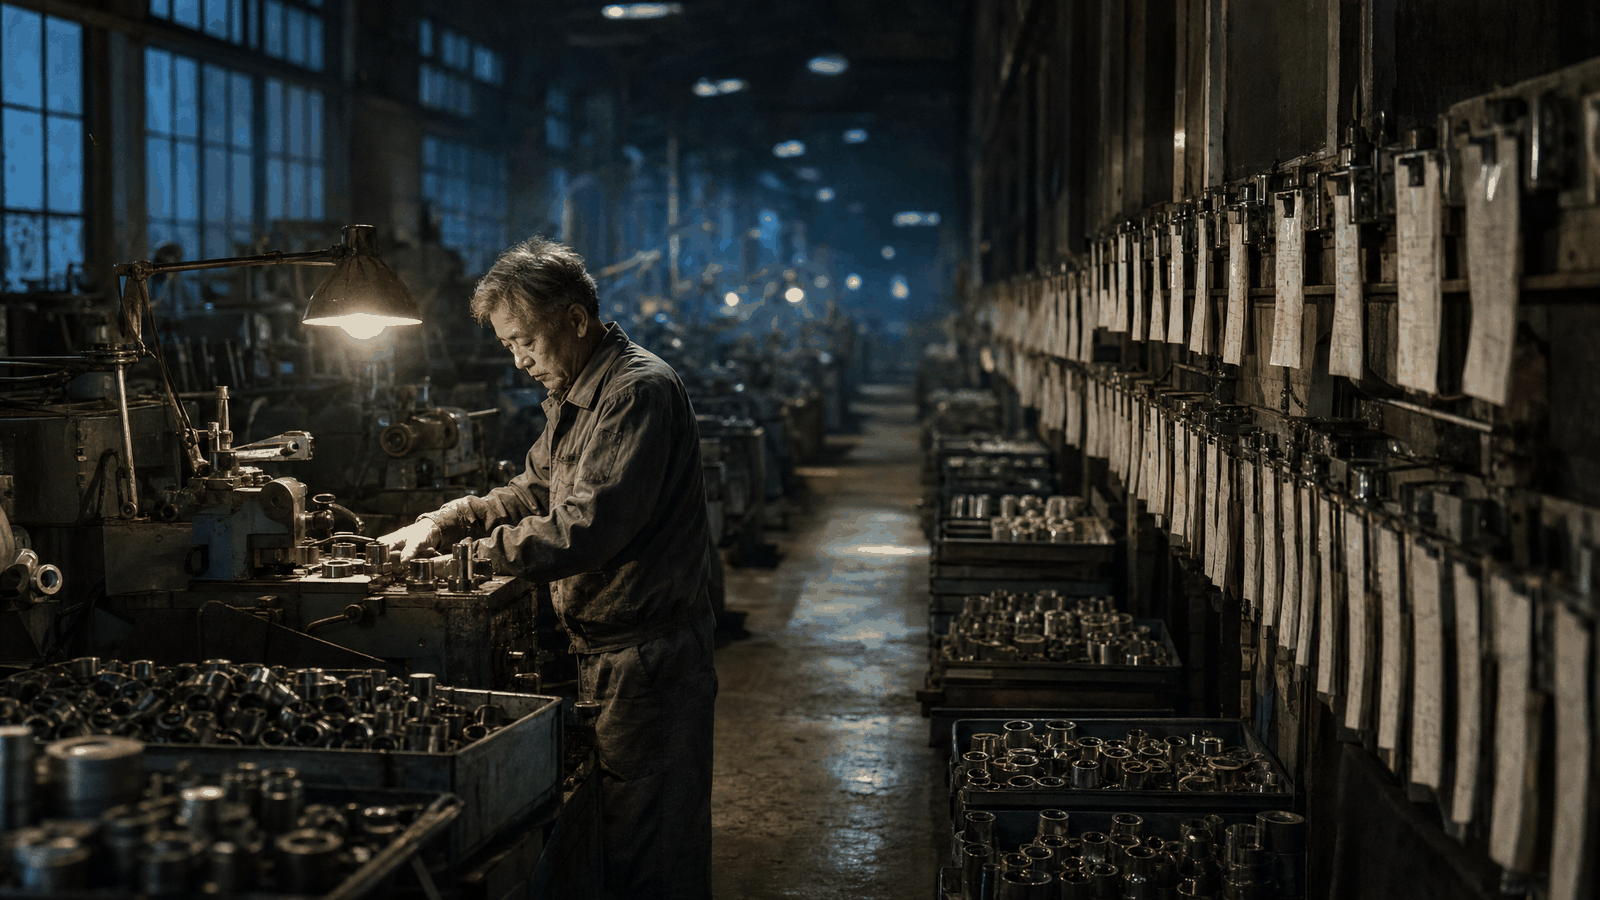
On the 2026-10-04 episode of Investor's Sunday, IHARA SCIENCE chairman Takuo Nakano describes taking over a company carrying ¥3.5bn in accumulated losses in 1999 and turning it around through cash-bleed control, receivables conversion, and making profit visible on the shop floor. Personal listening notes, educational only, not investment advice; figures come from the speaker's own recollection with no public filings to check against.
Contents
Thread follows needle, and you get a curtain; needle follows thread, and you get no garment at all.
—— Huainanzi, “Fanlun” chapter (Western Han; translated by the author)
The relaunch episode of Investor’s Sunday on 4 October 2026 featured Takuo Nakano, chairman of IHARA SCIENCE. When he took the president’s seat in 1999, the company carried ¥3.5bn in accumulated losses, ¥2.3bn in debt and ¥2.5bn in bad receivables against annual revenue of only ¥5bn; by 2023, the year it went private through an MBO, revenue was ¥22bn with operating profit above ¥4bn — an operating margin over 20%. Nakano laid out the turnaround as three steps in a fixed order: cut another ¥10m of monthly outflow to stop the bleeding, then renegotiate receivables into cash customer by customer (he converted 60%), and only then make profit visible on the shop floor — how many units this hour, at what price, against what material cost. One condition makes the whole thing work: he sells pipe fittings, and one missing fitting stops the entire machine. In a business where substitutes are a phone call away, the same process buys far less pricing room.
I used to file stories like this under “found a new growth curve”
When I see a manufacturer posting a 20% operating margin, my first move is to hunt for a technical moat — patents, material chemistry, a process nobody else can run. When I see a company near collapse, I look for its next market.
IHARA SCIENCE fits that template on the surface. They started in hydraulics: when machinery moved from cams and linkages to hydraulic drive, nobody made fittings that held up under high pressure, so they did, and rode Japan’s growth decades upward. Nakano is blunt about that period — the big manufacturers adopted their parts without asking questions, and growth came without much effort. Then the next shift arrived, electric actuation displaced hydraulics, and demand fell. Today semiconductor-related work is roughly 20% of the company.
Follow the template and the headline writes itself: old hydraulics shop pivots into semiconductors. One thing refuses to fit. In 1999 he had no new product. He says the company held “only things you could buy anywhere,” and the semiconductor business he inherited from the previous president was zero — what he inherited was the instruction “hydraulics is dying, go find a new market.” When he took that instruction to customers, they barely engaged: nobody’s buying semiconductor parts from a newcomer.
So the new curve is not the starting point. It grew out of what came later. The thing I had backwards was the order of causation.
The three things he did had nothing to do with products
He describes that first year concretely. Creditors queued at the door all day; handling them consumed the day and left no time to think. Suppliers passed a board resolution to stop shipping material to them. The bank cut off lending. A peer firm holding their notes came in tears because no bank would discount the paper.
What he worked out is almost plain: A equals B minus C, and the job is making A positive. He calls it “arithmetic management,” and says dropping it to the level of a household budget made it legible. To find thinking time he started getting up at 3:30 am and using the hours until he left at seven.
Step one, stop the bleeding. He calculated that another ¥10m of monthly savings would hold. Note that this came after years of wage and expense cuts already taken. His method: every payment slip came to his desk, and nothing he had not approved got paid — anything not strictly required was cut, or deferred until cash existed. He took office at the end of April and hit the number by September.
Step two, manufacture cash. A normal failing company has assets to sell. They had debt and a pile of receivables, held as notes. It was a financial crisis, customers had no cash either, and the conversation should have been impossible. He had it anyway, customer by customer, and converted 60%. His own takeaway: under terrible conditions, serious effort still produces something.
Step three, and only now, earn profit. He went to the floor and asked for profit, and the floor pushed back: do you even know this place, we work till midnight and still post losses, and you tell us to produce profit. He thought about it and concluded they knew the word “profit” and not the thing. So he made profit visible: worker A, nine to ten o’clock, this many units, this unit price, this material cost, this contribution margin. People understood it immediately — “chairman, so this is profit?”, “so we make this number bigger.” Productivity rose 40% in short order, the first year turned positive, and profit went ¥200m, then ¥400m, then ¥900m. His estimate of waste is six parts in ten; about four parts of the work creates value, so improving that six moves productivity without heroics.
The moat was defined only afterwards, and defined narrowly: 100% on-time delivery, 100% response to quote requests. About 7,000 order lines arrive daily from a scattered customer base, short-dated and irregular, landing in weekly waves. Nakano says 90% equals zero — one missing fitting and the bullet train does not move, and a customer with eight on time and two late is still a customer with a problem. He notes that some executives will state a 90% on-time rate out loud; to him anything short of 100 carries no meaning.
What I did not expect is his refusal to manage it with software. The standard answer is a scheduling system; his judgement was that the system route never reaches 100, so most of the mechanism stays deliberately analogue. Slips arrive, each line stands them on a rack by the date it owes, the heavy days and light days are visible, and how to hold the date is left to the person doing it. His phrase: not managing is the best management.
At first everyone said it was impossible. His answer was to take one line himself — finish that day’s load even if it ran to midnight, then do it again the next day, for a week, until that line’s delays hit zero. Then he asked the other lines one question: that line did it, why can’t yours. The plants went and asked each other for the method, and he says he spent little effort after that.
Value-based pricing came last. Items once sold three for ¥1,000 were repriced at ¥10,000 each. The customer’s response was “if you can do it for ¥10,000 that saves us, please.” He pushed this for three years, says it is still incomplete, and it underwrites the ¥30bn revenue and 30% operating margin he now targets. He bundles it as “four-wants capability”: what the customer wants, when they want it, in the shape they want, at the cost performance they want.
Now I look at the boring delivery numbers first
My corrected view: operational quality can be the source of a high margin. Copycat products plus punctuality plus willingness to alter a spec took a late entrant to the top of its category — Nakano says it without flinching, they built knock-offs of the first movers, and the difference was lead time plus accepting the “can you change just this part” requests nobody else accepted.
The use of this for a reader sits in a common misread. A pretty margin gets written up as a technical moat, and then the durability question gets asked in patent terms — what happens when it expires, what happens when rivals catch up. The question worth asking is whether the company sells a specification or a promise. IHARA SCIENCE sells a promise, so the things to check become lead time, late rate, rush-order acceptance, complaints — numbers with no dedicated line in any filing. Promise-based advantage decays differently too: it rests on organisational discipline, and the warning signs are staff turnover and slipping delivery quality rather than someone’s new technology routing around it.
The second misread concerns how to hear a company announcing a move into a hot sector. Nakano’s 20% of revenue from semiconductors was won with lead time and customisation, and the three years of bleed control, cash conversion and productivity work were the entry ticket. So when I hear a pivot story now, I go back and check whether the old business fixed its delivery numbers first. A pivot announced before that fix usually collects a valuation rather than orders.
The limits deserve saying. The figures come from his own recollection, and after the 2023 delisting there are no public filings to check them against. The 100% figure is an internal definition, hard to verify from outside, and fittings allow more than one way to score a due date. The bigger unanswered question: this discipline was built by a founder-grade figure standing on a production line himself. He stepped up to chairman in 2015, took the company private in 2023, and returned as representative chairman last year. Whether discipline of that origin survives a handover is something the episode leaves open. The same guest returns next week to discuss the MBO, and that is the question I plan to bring.
One thing to take with you
Promise work has no partial credit. Something done to 90% lands on the other person exactly like something not done — they have to rearrange, re-confirm, find a backup, and none of that cost drops by a tenth because you got nine tenths of the way. Nakano pushes the line to its extreme: 90% on time equals zero. What struck me is that the line holds whenever someone builds on top of what you hand over, and in ordinary life more things get built on than I had assumed.
Something I tried: pick one small thing you promised someone and have been delivering at eight or nine tenths — the pickup time, the weekly call to your parents, the “I’ll get back to you today” you tell a colleague — and take it to ten tenths this week, then write down what you changed to get there. When I did it, what changed was the arrangements around it, not the amount of effort.
This article is an educational discussion of investment method. It is not advice to buy or sell any individual security, offers no target prices, and does not analyze any current holding. Investing carries risk; make your own decisions or consult a qualified professional.
Comments
Loading comments…