An Economy So Good No One Can Live In It: Notes on Jill Schlesinger's Visit to The Compound
Listening notes on The Compound and Friends, 23 Oct 2026. CBS News business analyst Jill Schlesinger on 194,000 initial jobless claims, falling consumer charge-offs, and an $8 bottle of water at the movies: why aggregate data and a household price list can both be right, how media negativity got built, and why the top half of the K has no price ceiling. Educational notes only, no investment advice and no individual stock calls.
Contents
In the second month he sells the new silk, in the fifth he sells the standing grain. He heals the sore before his eyes by cutting the flesh from his own heart.
—— Nie Yizhong, “Song of the Farming Family” (Tang dynasty, c. 9th century; my translation)
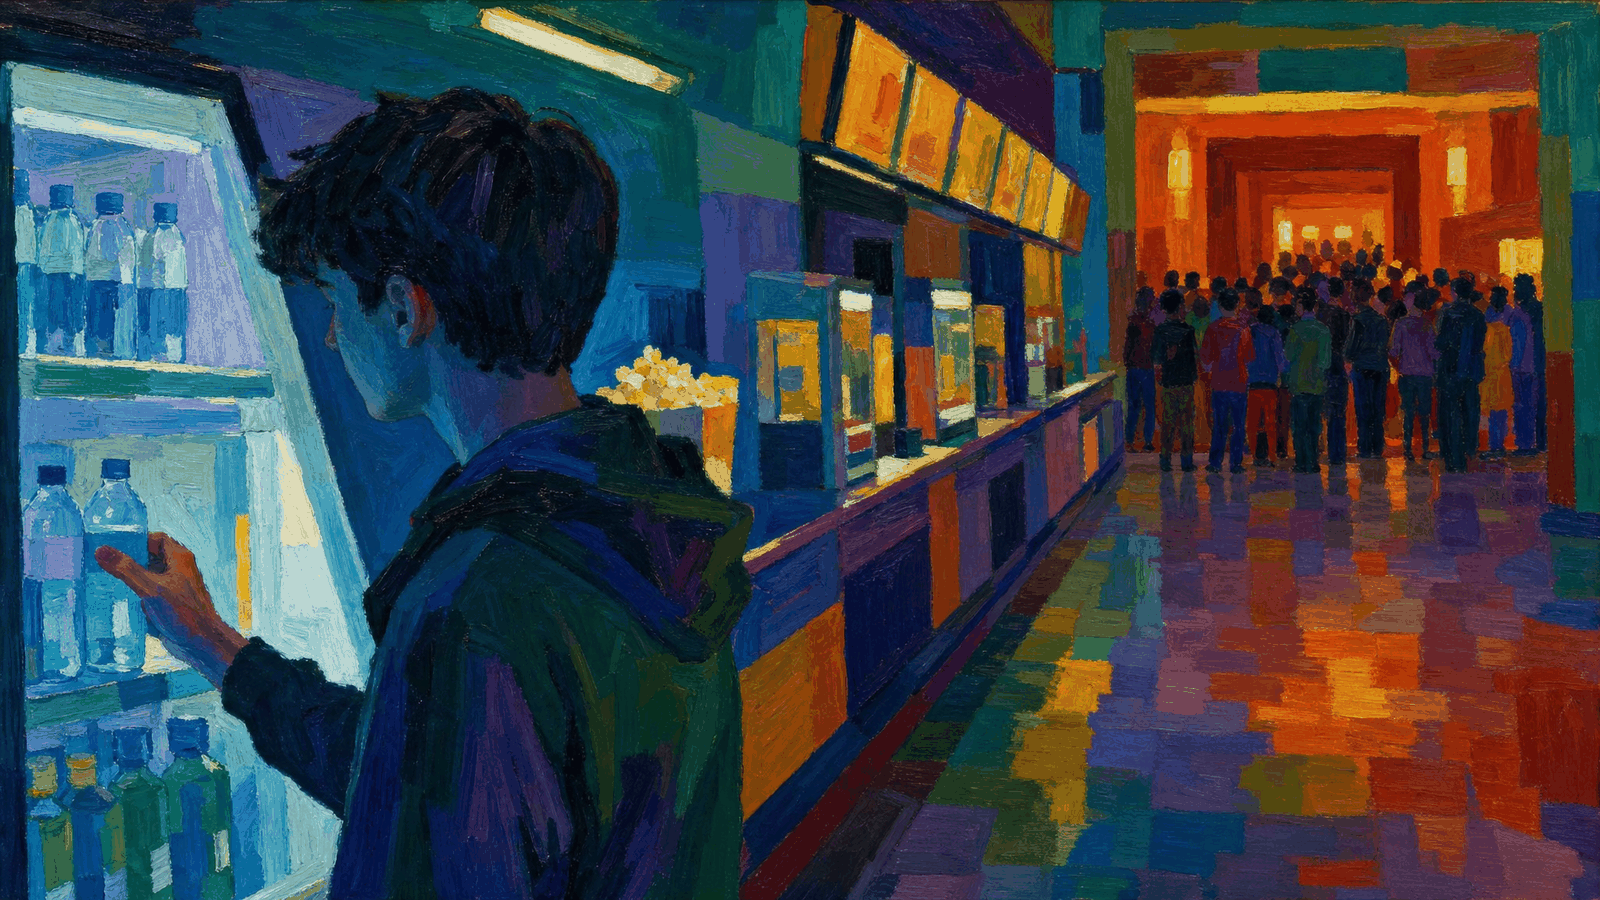
The 23 October 2026 episode of The Compound and Friends brought back CBS News business analyst Jill Schlesinger, who reported two numbers on air: initial jobless claims at 194,000 that week, the fourth lowest reading since the 1960s, and Bank of America’s consumer charge-offs still falling, with the banks saying the same thing for fifteen straight quarters. She also said that every time she goes on air and reports that the economy is holding up, the hate mail arrives. Host Josh Brown supplied the other half of the picture: the night before, at a movie theatre, a bottle of water cost eight dollars, and a kid laughed, put it back on the shelf, and walked to his seat without one. The episode lands on how both things hold at once — the aggregate series measure whether people have jobs and are paying their bills, a household measures what one paycheck now buys — and the condition under which both stay true is that the job is there and portfolios haven’t been down for a full year.
The data says the economy is fine, so why does my life feel tight?
Because those series measure flows, and you face a price list.

Schlesinger described her working problem. If she goes on air and says everything is great for the top 25% of earners and for people who already hold assets, she loses the rest of the audience. If she only covers the affordability story, she hasn’t told anyone the whole thing. Her line is that it’s not all good and not all bad, there’s something in the middle — and both sides write in angry.
One example makes the gap concrete. The Sunday the Russian oil news broke, her producers called because their heating oil bills were about to jump. She got up and looked it up: roughly 3% of US homes heat with oil, the rest run on gas or electricity. So the story is a real cost for truckers and farmers, and a non-event for most household budgets — yet the headline reads like the whole country is about to pay more for heat.

The longer-horizon gap came out of an argument with an old college friend who told her today’s kids are lazy. She went and pulled the data: inflation-adjusted starting incomes look about the same as his did. What changed is the cost of living, housing above all. Same job, and the generation that could commute and save a down payment has been replaced by one that may need two years at home first. Her verdict was blunt: if they’re your own kids, help them or don’t, but stop complaining about it while you do.

The sharpest moment was Brown’s: that kid and his anger aren’t made up, and he’s entitled to both. There is no column for that in the aggregate statistics.
Why is the news always negative?
It started as compensation and turned into a business model.
Brown’s version: financial media got caught with its pants down in 2008, the industry told itself it would never cover finance that way again, and then it went looking for the next crisis for seventeen years. He thinks that instinct has value — markets need skeptics, and the people shorting Tesla, doubting Bitcoin, or calling AI capex a bubble have probably helped prolong the cycle.
Schlesinger’s addition is that the engine has changed. Media is a business, it wants to make money, readers click negative headlines, so negative headlines get supplied. She wants to come on when the S&P is at an all-time high and explain how it got there, rather than being summoned only when it’s down 10%. When she says on air that AI investment and consumption are part of what’s powering the market, the hate mail comes anyway — her framing is that you can hate the data centres and still take in the fact that your 401(k) looks the way it does partly because of them. Both messages at once.
Brown got a live demonstration that week. He watched the Elizabeth Holmes documentary, which spends much of its runtime on whether a reporter misquoted her; thirty minutes later he got a text about a Wall Street Journal piece casting the Future Proof conference as a private credit sales pitch, when most of the thousands of advisers there are fiduciary CFPs. His takeaway is that this is the same mechanism as the daily AI headlines: everyone competes for eyeballs, and the competition includes YouTube and short video. Facebook had just reported record engagement the night before.
The part I keep thinking about is Schlesinger’s other half. She takes listener calls, and a 37-year-old woman told her she has $300,000 saved for retirement and feels behind. Her answer was that she isn’t behind, she’s doing great. The feeling didn’t come from the number. It came from the comparison list in her hand.
Tickets cost a fortune and still sell out — how?
Because everyone wants the same thing, so the top half of the market has no ceiling.
Brown’s 17-year-old texted that all his friends are going to a Calvin Harris show. Tickets were $600 and sold out, so resale only. Three more shows got added, and those were $700. Supply up, price up — because a city offers a million ways to spend a Tuesday night and everyone wants the one that’s spoken for.
Schlesinger walked through two Las Vegas hotels. The Fontainebleau was empty enough, she said, to throw a football across. Her own hotel, the Wynn Encore, was packed to the rafters. The difference is that social media decided which one was cool. Corporate America has noticed: United and Delta are raising miles requirements, Disney raises prices, all at the top of the K. Brown’s observation is that the middle gets pulled in too, because ambition plus the algorithm makes middle-class buyers want the same list as wealthy ones.
The counter-move showed up as well. Schlesinger can’t bring herself to pay $30 for a drink — of course she can afford it, and it hurts. She mentioned the uptick in mahjong, because four people can sit for two hours for nothing while lunch runs $80. After interviewing people across the income distribution, her summary was that there are many Americas. Ben’s version, quoted on air, is sharper: everyone says people with money are out of touch, and in fact everyone is in touch only with their own algorithm.
When does this reset?
Not on its own. Something external has to interrupt it.
Schlesinger admitted saying, in a 9 a.m. editorial meeting with 200 people on the line, that what the country needs is a decent selloff and a recession to reset things. It won her no friends. Brown’s objection is that recessions hit the people who can least afford them, and that recent history is all V-shaped recoveries. His test for a change in psychology is people seeing a year-over-year decline in their portfolios, and that hasn’t happened in a long time.
The other leg holding this up is labour. With immigration down, in some industries the immigrant pool was the whole pool. Healthcare demand is off the charts, and Schlesinger flagged the in-hospital nursing shortage specifically: nurses are leaving the floor for concierge practices, and the hard, genuinely good hospital jobs are going unfilled. Three years into the AI era, companies are holding on to their employees. Wage growth isn’t the unnatural 2021 kind, and it’s still growth. So as long as jobs hold and investments compound, people keep upgrading to first class and keep queuing outside the Amex lounge.
On AI, the episode’s turn is about cost. IBM’s CEO told investors that large enterprises are becoming far more aware of the true ROI of their AI spend, and more worried that some of it has no return. OpenAI introduced cheaper mid-range models in September; Anthropic released Haiku 5.5 for Claude this month, better performance at lower cost. Brown’s read is that 2027 moves from “whose model is best” to “whose is good enough and cheaper.” Meta’s print gave the other side: the stock touched 750 after hours and traded at 650 the next day, free cash flow turned negative for the first quarter since 2012, while ad impressions rose 10% year over year, average price per ad rose 14%, and 3.64 billion people used the apps. The call’s own description of the business was candid — revenue is driven by the ability to deliver engaging experiences and by the effectiveness of monetising that engagement.
So what do I do with any of this?
I treated the episode as a sorting exercise, in three layers.
Layer one: keep two ledgers apart. The aggregate series — claims, charge-offs, wages — answer whether I’m about to lose my income. My own price list answers what that income buys. Both can point opposite ways and both be right. I’ve made the mistake in the other direction: a year when the macro data looked lovely, I eased off checking my own cash flow, and found that rent and insurance had eaten half my savings rate. Now I do one thing each quarter — write down the year-over-year change in my three largest fixed costs. That number owes nothing to the news.
Layer two: look at who you’re measuring yourself against. The caller with $300,000 and the 17-year-old being dragged along by his friends’ concert list are running into the same mechanism: the comparison set is an algorithmic sample that includes only the people who could afford to go, because the ones who couldn’t don’t post. I thought about the times a peer’s posted return made my hands itch, and how I later found out they were posting a single position rather than a whole account. Wrong control group, wrong conclusion.

Layer three: notice what is getting more expensive where you hold no bargaining power. Brown said something about his own industry that stuck with me: the computation side of financial planning was solved by software a generation ago, and the hard part is attention — clients want someone who listens, who remembers what matters to them, who has a stake in things turning out well. AI lets his firm scale and gives the best advisers a third hand, and it doesn’t replace what people are actually paying for. I’ve started applying that test to my own work: which part of what I do is computation, and which part requires me in the room.

Schlesinger offered a working example of her own. There is no social media on her phone. It started when a flood of attacks on her identity arrived during a particular period, and the habit stayed. She said she doesn’t like being served information, she likes going to get it: government site subscriptions, the Times, the Journal, the FT, the New Yorker, New York Magazine, The Atlantic, The Economist, and sports coverage when she wants to goof off. She concedes it may hurt her career, since she can’t answer when someone asks whether she saw the thing going around. Her self-description: optimistic about each individual’s ability to move ahead, pessimistic about systems.
One more detail, the funniest in the episode and a lesson in attention budgeting. For the six years Brown kept his hair short he needed a cut every three weeks, so he kept five barber shops on rotation, because by the third visit the same barber starts asking what he thinks about the stock market. One of them sits up a staircase in an office lobby on Wall Street, where the barber barely speaks English and has no interest in him whatsoever. His review: perfect. You can file that under eccentricity, or you can file it under a man deciding how much attention he spends per week.
The One Thing to Take With You
One idea: the list you measure yourself against is an algorithmic sample, not the real distribution. The caller with $300,000 had nothing wrong with her number. The problem was the control group, and the control group had been chosen for her.
Here’s something I’ve tried that takes one sitting. Take a sheet of paper and write down the last three moments you felt behind. Next to each, write only one thing: where that information came from. Did a friend say it to your face, or did you scroll past it? Was it someone’s whole picture, or the side they chose to publish? When you’re done, a few of those lines will share a source. Take the app that shows up most, and move it off your home screen into a folder on the last page. This has nothing to do with money and everything to do with who’s picking your comparison set.
This article is an educational discussion of investment method. It is not advice to buy or sell any individual security, offers no target prices, and does not analyze any current holding. Investing carries risk; make your own decisions or consult a qualified professional.
Comments
Loading comments…