Why Can't Central Banks Shrink Their Balance Sheets? Two Diseases, Mirror Images
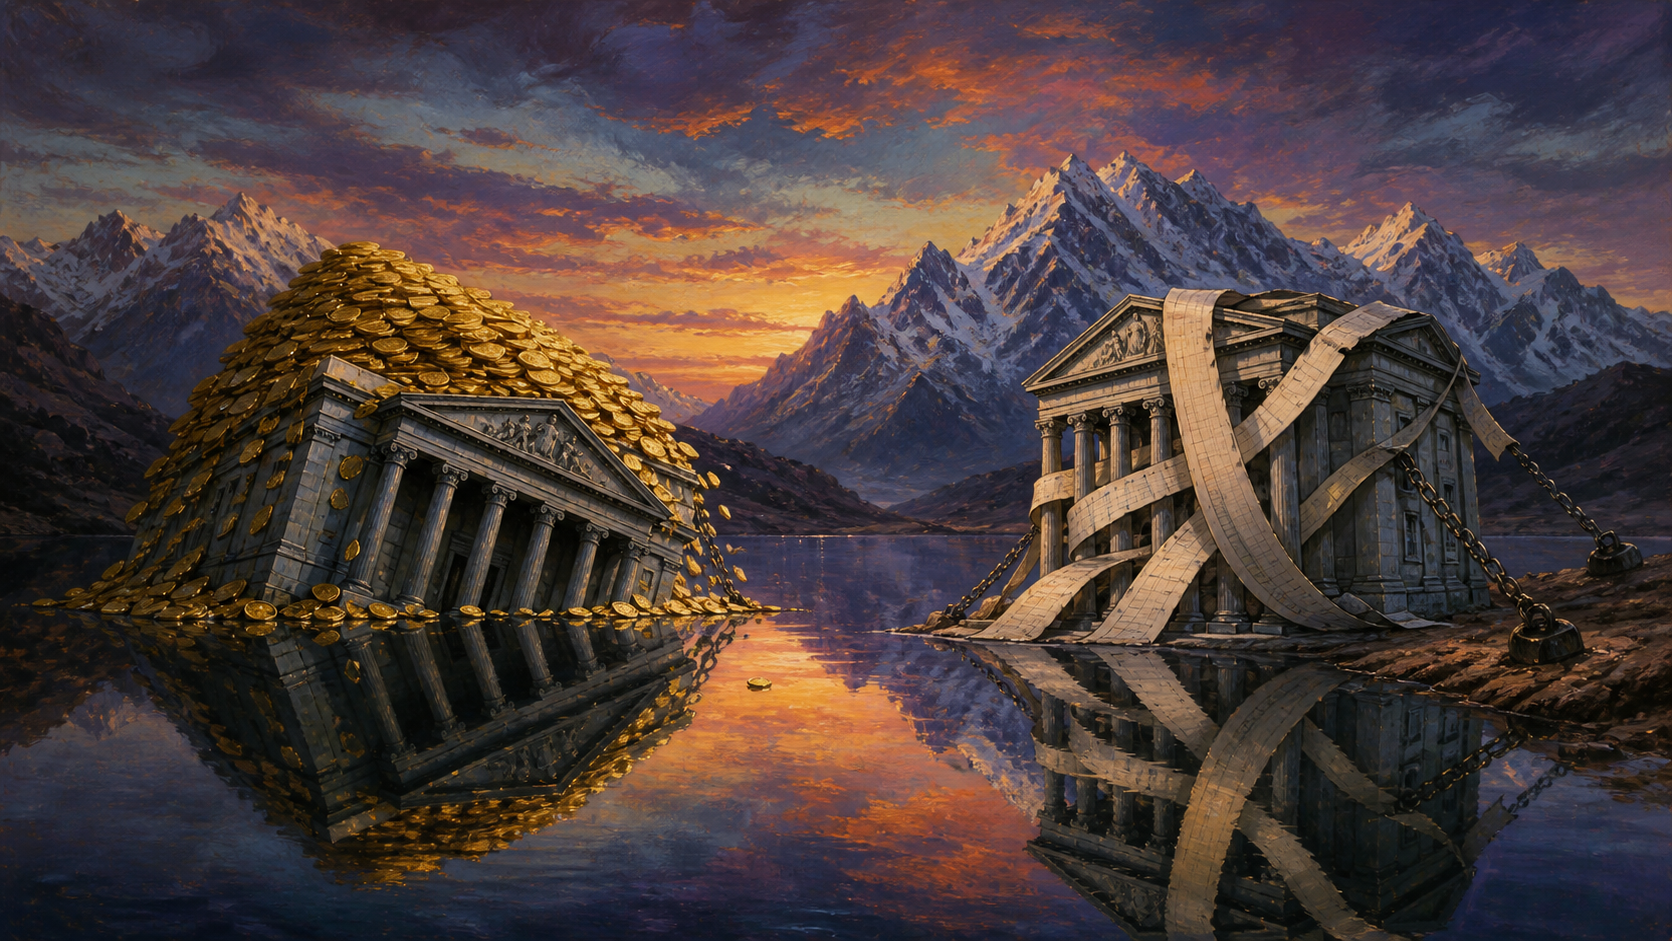
Switzerland's problem lives on the asset side; the Fed's lives on the liability side. Same symptom, opposite pathologies. Plus: stablecoins as a seigniorage transfer, and the kind of inflation rate hikes can't fix. Notes on a Macro Musings episode with Gianluca Benigno.
Contents
“Central bank balance sheets are too big and should shrink.” We’ve heard that sentence for a decade. Then I listened to Macro Musings interview the economist Gianluca Benigno (August 10, 2026) and realized “can’t shrink” describes two completely different diseases — and they happen to be mirror images of each other.
Benigno isn’t a pundit. He helped build the Global Supply Chain Pressure Index during his years at the New York Fed, and balance sheets are now his research beat. The episode covers three topics: the Swiss National Bank’s predicament, what stablecoins actually change, and why he doubts rate hikes can fix a certain kind of inflation. All three are better than they sound.
An asset-side disease and a liability-side disease
Start with Switzerland. The franc is a safe-haven currency; whenever the world panics, money floods in, the franc appreciates, and Switzerland imports deflation. The SNB’s answer has been to buy foreign assets to lean against the exchange rate — euro bonds, dollar bonds, even US equities.
How far has this gone? By the SNB’s own annual report, total assets stood around 894 billion francs at the end of 2025, of which roughly 759 billion was foreign-currency investments. Foreign positions are about eighty-five percent of the entire balance sheet.
That produces what Benigno calls a fiscal-scale trap. The bigger the balance sheet, the more a one-percent currency move swings the P&L. And since SNB profits get distributed to the federal government and the cantons, local budgets ride the exchange rate like a roller coaster — distributions were zero in 2022 and 2023, then four billion francs for 2025. Try planning a budget around that. Worse, the sheet resists shrinking: selling foreign assets means buying back francs, which pushes the franc up, which recreates the original problem. This is a disease of the asset side.
America’s version grows on the other side of the ledger. Quantitative easing created a mountain of bank deposits. More deposits raised banks’ demand for reserves. So when the Fed tries to shrink, it discovers the financial system can no longer function at the old size. This is a disease of the liability side.
Same symptom, opposite pathologies, entirely different medicine. That contrast alone is worth the hour.

One detail I enjoyed: the SNB holds US stocks but doesn’t publish the details, so researchers reconstruct its portfolio from SEC filings. To study the Swiss central bank you go digging through American regulatory databases. That tells you something about what modern central banks have become.
Stablecoins: not money printing, a seigniorage handover
On stablecoins, Benigno offers a frame that cuts against the market narrative.
The usual story says stablecoins create new demand for Treasuries. His balance-sheet walk-through says: at the moment a stablecoin is minted, the system’s total money supply barely changes. What changes is the distribution. A deposit that used to earn a bank its spread now sits with a stablecoin issuer, whose token pays no interest while its T-bill reserves do. The spread — the seigniorage — has changed hands. Nothing was conjured.

He does flag a second-order effect worth watching: as retail deposits migrate into custodial, wholesale-style deposits with different regulatory treatment, reserve demand at the margin goes up. Follow the loop around and stablecoin growth feeds back into the size of the Fed’s balance sheet after all.
I’d add an angle the episode skips. His analysis is all steady-state reallocation. Now imagine stablecoins at several trillion dollars, with issuers as a class of T-bill holders who are completely insensitive to yield. In calm times that suppresses short-end rates — sounds nice. In a redemption run, those same holders become forced sellers, all in the same direction. A buyer who doesn’t care about yield is, in the wrong scenario, a seller who doesn’t care about price. The flip side of a compression premium is an amplified tail. The Treasury market already rehearsed this in March 2020.
The inflation that rate hikes can’t fix
The last segment covers his research using the supply-chain pressure index: when a global supply shock gets large enough, inflation’s behavior changes character. It stops being a spike that fades and starts propagating through production networks, developing persistence.
His policy conclusion is uncomfortable: these shocks hit essentials — energy, food — that households can’t cut. Raising rates doesn’t touch the source of the shock and lands a second blow on the most exposed families. He says it plainly in the episode: with this type of shock, it’s not obvious to him that hiking is the right response.
You can disagree. But he leaves you with a usable question: next time an inflation print lands, ask whether it’s demand-pulled or supply-broken, and whether the break is big enough to change character. The same CPI number can sit on top of two different scripts, and the two scripts call for different portfolios.
One thing to take with you
The line that stayed with me from this episode: one symptom can have two opposite causes, and the medicine is completely different. Switzerland and America both can’t shrink their balance sheets, one sick on the asset side, one on the liability side, and while listening I kept thinking about my own “tried everything, nothing works” problems and whether I had ever asked which side they were on.
Here’s a crude thing I tried: take one problem that has nagged you for years — can’t save, can’t sleep, keep fighting with the same person. Divide a sheet into two columns. On the left, causes that sit on the “coming in” side; on the right, causes on the “going out” side, at least one per column. Then beside each cause, write one check that would settle it within a month. When I did this for saving money, I wrote three causes per column and realised every fix I’d tried in five years lived in the right column; I had never touched the left. A month later, look back: whichever column’s check answers first is the side to start treating.
This article is an educational discussion of investment method. It is not advice to buy or sell any individual security, offers no target prices, and does not analyze any current holding. Investing carries risk; make your own decisions or consult a qualified professional.