Acquired | Home Depot: A 25-Cent Washer and a Company That Swapped Out Every Founding Tactic
Notes after listening to Acquired's 2026-09-13 episode on Home Depot: how four founders came together, how an outside CEO doubled revenue while the stock went nowhere, and how his successor doubled sales per store by halting new openings. An educational reading note, not investment advice, and not a recommendation of any stock.
There is some of the same fitness in a man’s building his own house that there is in a bird’s building its own nest.
— Henry David Thoreau, Walden, “Economy” (1854)
What This Episode Covers
Acquired’s 2026-09-13 episode is about Home Depot (ticker HD). I used to think of it as a big box next to a shopping center. It turns out to be the world’s largest specialty retailer: roughly $350 billion in market cap, operating only in North America, with 470,000 employees — more than any bank or any restaurant chain. It went public in 1981, a year after Apple. $1,000 at the IPO with dividends reinvested is worth about $17 million today; the same money in the S&P 500 would be about $170,000.
Ben and David tell it as a retail Avengers movie: four people assemble, the company grows, an outside CEO nearly takes it apart, and a lawyer-turned-successor brings it back.
Key Takeaways
1. The company began with a firing. Bernie Marcus and Arthur Blank had made Los Angeles hardware chain Handy Dan the best operator in the industry, without owning a single share. New York banker Ken Langone flipped through his Moody’s manual, saw the stock at $3 with $1.50 of after-tax earnings per share, flew out for lunch the next day, and went home to buy nearly 20% of the company. The only holdout was a Catholic congregation in Brooklyn, whose priest asked: “Are you Catholic? Then under the pain of hell, tell me what I should do.” He answered: “Keep it.” Later Bernie, tired of Ken’s feud with the parent company’s boss, begged him to sell. Ken did. Three months later both Bernie and Arthur were fired. At breakfast the next day Ken told Bernie he’d just been kicked in the ass with a golden horseshoe — now they’d go build the store Bernie had described.
2. The idea came from Costco’s predecessor; the model diverged on day one. Bernie had visited Sol Price’s Price Club in San Diego: the warehouse is the store, no back room, no middlemen. He brought that to hardware and added two things Price Club lacked: 25,000 SKUs (versus roughly 4,000) and staff who knew the trade. Everyone knows how to use toilet paper; few people know how to build a deck. Gross margin was set at 30% against an industry norm of 45%, with prices 10% to 25% below competitors.
3. So short on money they had to stage the store. Ross Perot was going to put up $2 million for 70% of the company. The deal died over Bernie’s car — an old Cadillac. Perot said his people only drove Chevrolets; Bernie walked. At today’s market value, assuming Perot held, that car cost him over $200 billion. Ken instead lined up 40 people at $50,000 each, on terms he wrote himself, with investors taking 50%. It still wasn’t enough to fill the shelves, so merchandising genius Pat Farrah (whose previous store collapsed because he never paid his suppliers’ invoices) borrowed 500 empty boxes and found 2,000 empty paint cans per store, stacked ten feet high. The night before opening, the store managers had the floors polished. Farrah saw it at 4 a.m., got the two founders out of bed, and the three of them drove forklifts around to scuff the floor so the place looked used. Bernie later wrote: our stores are action places.
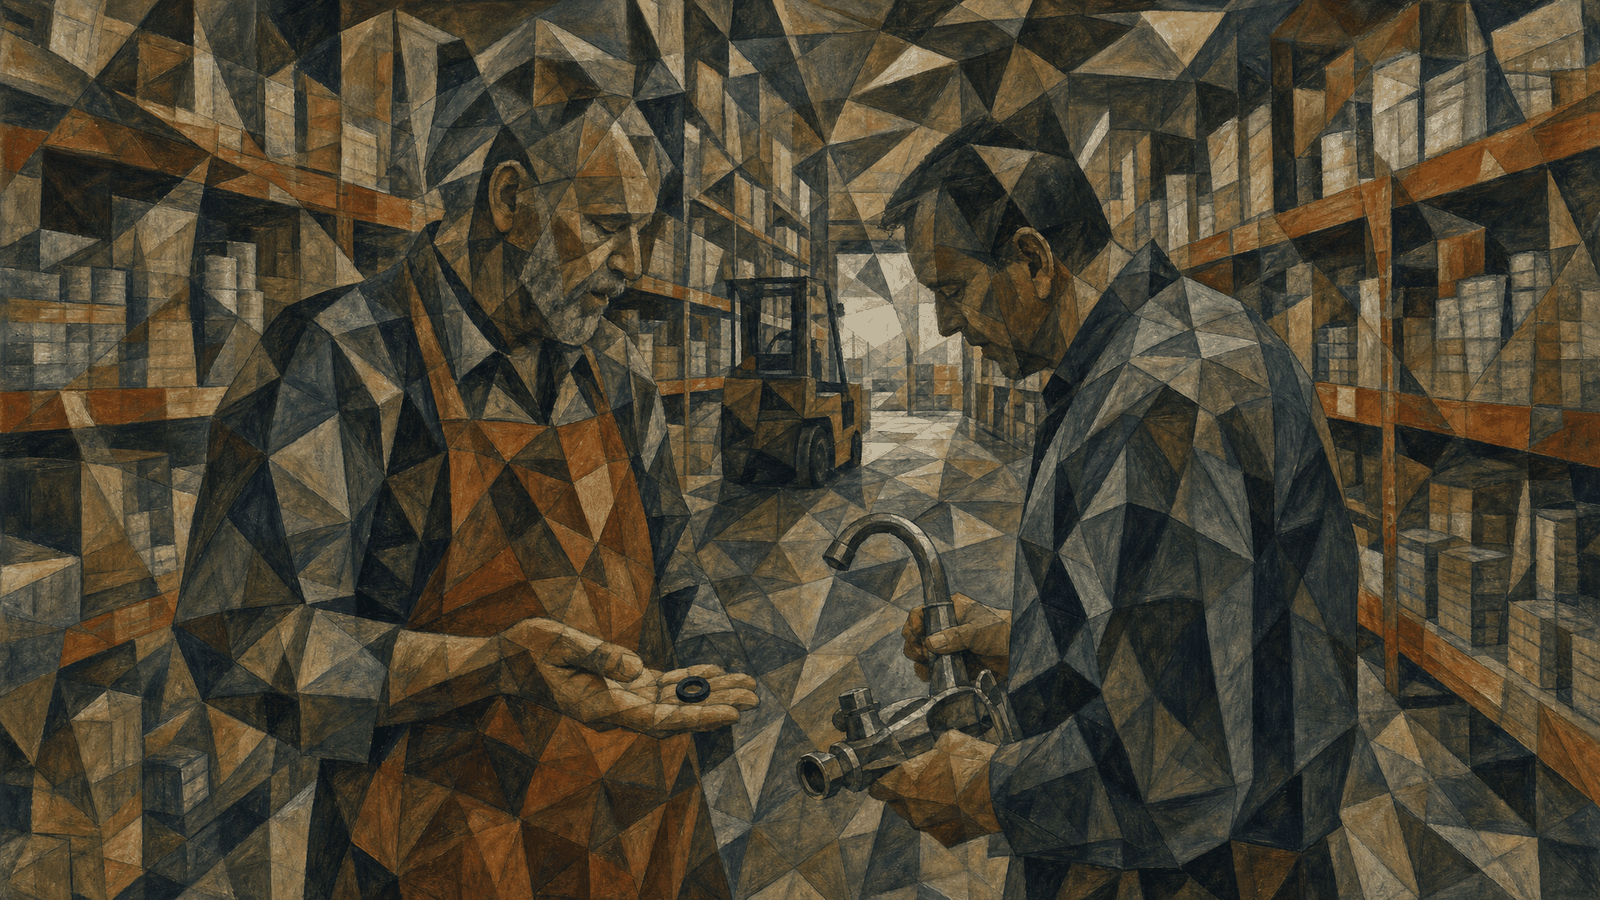
4. The moat lived in the associates. Home Depot recruited plumbers, electricians, and carpenters as store staff. Contracting meant lumpy income, endless driving, and manual labor with nothing to fall back on if you got old or hurt; the store paid less but offered steady hours and security. Then the company put stock in their hands: hourly workers could buy at a 15% discount, with the company covering any loss below their purchase price. The legend: a customer comes in with a leaking faucet, ready to spend $200 on a new one. The associate says a 25-cent washer will fix it. A few weeks later the family comes back and does a $100,000 kitchen remodel. When someone joked the associate had lost a sale, Bernie called to say he should be promoted. Later CEO Frank Blake put it this way: the best sign of cultural health is walking into the break room and seeing associates watching the stock price.
5. Six years of doubled revenue and a stock that didn’t move. In 2000 the board brought in Bob Nardelli, a runner-up in GE’s CEO succession. For four years the numbers looked great: revenue and profit doubled, store count went from 1,100 to 2,000. Underneath: associates per store fell from about 200 to 170, many replaced with part-timers; store managers were now preferred to have college degrees, closing the promotion path from the floor; customer satisfaction fell to last among major US retailers. He refused to tie his pay to the stock price. Over five years Home Depot’s stock fell 12% while Lowe’s rose 173%. At the 2006 annual meeting not a single director showed up. He was fired the following January.
6. Stop opening stores, double sales per store. His successor, Frank Blake, was a lawyer who had never run a P&L; his son worked in a store. His first call as CEO was to Bernie, who had fallen out with the company, and the first store they walked together was a Costco. He took 90% of his pay in options, halted the new-store pipeline, sold the wholesale distribution business for $8.3 billion, and put all of it into buybacks — repurchasing 30% of shares over his tenure, mostly at $30 to $50, versus roughly $340 today. The company had 2,300 stores in 2008 and has 2,400 today; over the next eleven years revenue went from $70 billion to $130 billion and sales per store from $30 million to $65 million. A big piece of that came from ordering online and picking up in store: when you run out of grout halfway through a tiling job on a Sunday afternoon, nobody waits two days for delivery. And the 6,000 pounds of lumber for a deck won’t fit in an Amazon van.
7. It got this big because several factors multiplied. Ben’s closing answer was an equation: the warehouse format works for hardware (nobody minds buying hammers in a warehouse) × a huge market (US home-improvement stores, about $300 billion) × dominant share (Home Depot 51%, Lowe’s 29%, the next player under 5%) × an aging housing stock. The median age of a US home stayed around 23 years from 1940 to 1980, started rising the year Home Depot was founded, and is 42 today. David added one more factor: high homeownership and the 30-year mortgage. China’s housing market is larger than America’s, yet Home Depot failed there — fixing your own house isn’t considered a virtue, and the wealthy mostly live in city apartments.
Further Thoughts
Revenue and profit are growing — why isn’t the stock?
This is where I often get stuck reading financials: the company says it’s growing, the numbers are growing, and the stock ignores it. Nardelli’s six years are a clean example, so I tried peeling it back layer by layer.
Layer one: where does the growth come from? Total revenue can double in two ways — more stores, or each store selling more. The first is bought with capital; the second comes from the stores getting better. Nardelli’s growth came mostly from new stores. Flat same-store sales meant the old stores weren’t improving; new stores just copied the same performance a few more times.
Layer two: what is the market calculating? A stock price discounts future cash flows. When $20 billion of buybacks and dividends during his tenure couldn’t lift the price, the market was saying it didn’t believe future earnings would exceed today’s. Fewer associates, bottom-ranked satisfaction, plus gross margin pushed from around 30% to 33% — these moves made this year’s numbers look good at the cost of next year’s traffic.
Layer three: who is driving these moves? Ben reversed himself on air. He first defended Nardelli: pay tied to the stock price seems unfair, since the price is just what outsiders think of you. By the end he’d changed his mind: people paid on current numbers will pump current numbers; people paid on the stock have a reason to store value inside the company. Home Depot’s model relied on associates believing “serve well → sales grow → stock rises → I get rich.” When the CEO steps out of that chain, it’s hard for the people under him to stay in it.
What I do now: when I see “revenue up, stock flat,” I look for a per-unit productivity number — same-store sales, sales per store, sales per employee — and check whether it’s growing. If it is, the market may not have noticed yet. If it isn’t, the market may have noticed already. This reading has a failure case: if new stores earn high returns on their own, growing by opening stores is fine. Blake later bought back part of the distribution business and spent $18.25 billion on roofing distributor SRS. Expanding into adjacencies can work; Nardelli lost on timing and foundation.
A stock you hold is down 70% — how do you tell whether to stay or go?
Ken Langone never sold a share of Home Depot. Down 66% in 1985, 70% in 2002, 70% again in 2008 — he held, and his stake is worth about $6 billion today. Someone who bought at the 1999 peak waited 12 years to break even; a great company bought at too high a price still makes you wait.
It’s easy to read this as “hold good companies and you win.” I think the episode offers something finer. During the Nardelli years Ken didn’t just sit tight: as lead director he called the special board meeting that fired the CEO, pushed Blake into the job, and then pushed the company to buy back stock through the financial crisis. He could stay because he knew where the company’s money-making mechanism lived, and he could see where it was breaking.
I break it into three steps — here’s how I think about it:
Step one: write down in one sentence how the company makes money. For Home Depot: knowledgeable associates give customers the confidence to take on bigger projects; volume earns lower prices from suppliers; those prices get passed back to customers.
Step two: ask whether this drawdown hit from outside or inside. When housing collapsed from 2007 to 2010, revenue fell, but houses kept aging and the mechanism survived — that’s a cycle. When Nardelli cut associates and blocked promotions, he hit the mechanism itself — that’s structural. A cycle you can wait out; with a structural break, you look for whether someone is fixing it.
Step three: pick a number that lights up before the stock does. At Home Depot, same-store sales and customer satisfaction flagged trouble years ahead of the share price.
Resources
- Acquired, “Home Depot,” 2026-09-13
- Bernie Marcus and Arthur Blank, Built from Scratch (1999): the founders’ own account, including the empty boxes and the forklift-scuffed floors
- Ken Langone, I Love Capitalism! (2018): Langone’s memoir, including the fight over Nardelli’s appointment
- Worldly Partners (Arvind Navaratnam), Home Depot study, worldlypartners.com
- Hamilton Helmer, 7 Powers: the framework used in the episode’s analysis
- Acquired’s episodes on Costco, Walmart, and IKEA, for comparison
One Thing to Take Away
Near the end, Ben pulled out the founding rules from Built from Scratch and checked them against the store he’d visited the week before. The book says no aisle numbers, so associates have to walk customers to the item — the store has aisle numbers now. The book says no back-door discounts for contractors — there’s a pro desk with bulk pricing now. The book says everyday low prices, no promotions — he’d just received an email reading “up to 30% off, limited time.” His and David’s conclusion: keep the founding values; most founding tactics have to change. Nardelli swapped out the values; Blake swapped out the tactics.
A practice goes stale; the problem it was built to solve stays. The problem is what you keep.
One thing I’ve tried: pick a practice you’ve kept for three years or more — a household rule, a work process, a way of raising your kids. On a sheet of paper, write two lines. First line: what problem was it meant to solve? Second line: does that problem still exist today? If it does, look for an easier new way to handle it; if it doesn’t, you can let the practice go.
This article is an educational discussion of investment method. It is not advice to buy or sell any individual security, offers no target prices, and does not analyze any current holding. Investing carries risk; make your own decisions or consult a qualified professional.